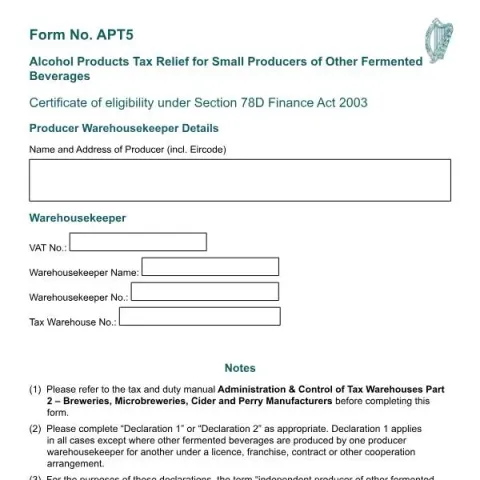
Understanding the APT5 Certificate: A Guide for Small Producers of Fermented Beverages in Ireland
The APT5 form, officially titled “Alcohol Products Tax Relief for Small Producers of Other Fermented Beverages – Certificate of Eligibility under Section 78D Finance Act 2003”, is an essential document issued by the Irish Revenue Commissioners. It serves as an official certification that small-scale producers of fermented beverages qualify for specific relief from Alcohol Products Tax (APT). This guide explains the purpose of the certificate, eligibility criteria, application process, and how it can be used by qualifying producers.
What is the Purpose of the APT5 Certificate?
The primary role of the APT5 certificate is to confirm that a small producer of other fermented beverages—such as cider, perry, or similar drinks—meets the legal criteria to benefit from tax relief under Irish law. Specifically, it facilitates the application of relief provisions outlined in Section 78D of the Finance Act 2003, as amended by subsequent legislation. By obtaining this certificate, eligible producers can reduce their alcohol products tax liabilities, making their operations more economically viable.
This document is also necessary for compliance with the administrative requirements of the Irish Revenue Commissioners, ensuring that producers adhere to legal standards and accurately declare their production volumes and ownership structures.
Who Can Obtain the Certificate?
To qualify for the APT5 certificate, a producer must meet specific criteria as an independent or associated small producer of fermented beverages:
- Independent Producer: The producer must be physically separate from other producers of fermented beverages, with no significant production under licensing, franchise, or contractual arrangements exceeding 50% of their total output.
- Multiple Producers: If a producer owns or operates more than one small producer, the combined total production must not exceed 10,000 hectolitres annually.
- Production Volume: The annual production of the fermented beverages must be within the thresholds set by the legislation, generally under 10,000 hectolitres for individual or combined producers.
Additionally, producers must demonstrate that their operations are independent and separate from larger commercial entities, ensuring they meet the legal definition of a small producer under the relevant legislation.
How to Apply for the Certificate
Applying for the APT5 certificate involves submitting a detailed declaration to the Revenue Commissioners, including:
- Producer Details: Name, address (including Eircode), and VAT number if applicable.
- Production Data: The volume of fermented beverages produced in the previous calendar year.
- Ownership and Independence Declarations: Statements affirming the independence of the producer(s) and their compliance with criteria concerning licensing and contractual arrangements.
The application process requires completing the relevant declarations (Declaration 1 or Declaration 2), which confirm the producer’s qualification status, production volume, and independence. These declarations must be signed by the producer or an authorized representative. It is crucial to provide accurate and truthful information, as false declarations can lead to penalties.
Validity and Usage of the Certificate
Once issued, the APT5 certificate remains valid for the period specified within the document, typically covering a calendar year. Producers should retain their certificate as part of their official records and present it to the Revenue Commissioners if requested during audits or inspections.
The certificate enables small producers to claim relief from alcohol products tax on their eligible fermented beverages, thereby reducing their tax liabilities. It also serves as proof of eligibility should the producer’s operations be scrutinized by tax authorities.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Important Considerations
Producers should be aware of the following:
- Accurate Record-Keeping: Maintaining detailed production records is essential to substantiate claims made in declarations.
- Legal Compliance: False statements or falsification of documents can result in severe penalties, including fines or prosecution.
- Renewal and Review: The certificate’s validity may require renewal or updating if production circumstances change.
For detailed guidance, producers are encouraged to consult the official tax and duty manual, specifically the section on the administration and control of tax warehouses for breweries, microbreweries, and fermented beverage manufacturers, or seek professional advice to ensure compliance with all legal obligations.
Conclusion
The APT5 certificate is a vital tool for small producers of fermented beverages in Ireland seeking to benefit from alcohol products tax relief. Understanding its purpose, eligibility criteria, and application process helps producers navigate the legal framework effectively, supporting their business growth while maintaining compliance with Irish tax law.