Understanding the APT3 Certificate of Eligibility for Microbreweries in Ireland
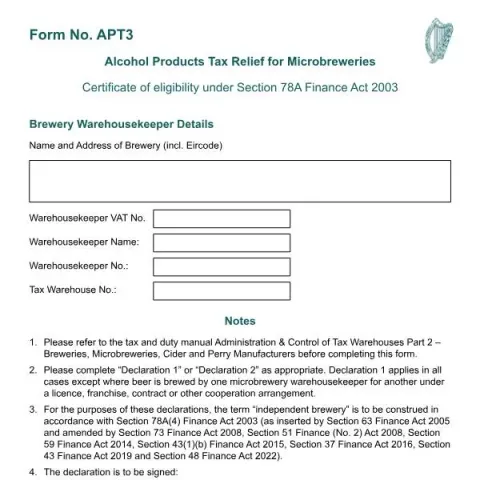
The Irish Revenue Commissioners provide a specific official document known as the Form No. APT3, which serves as the Certificate of Eligibility under Section 78A of the Finance Act 2003. This certificate is essential for microbreweries seeking to benefit from alcohol products tax relief. It confirms that the brewery qualifies under the criteria set by Irish tax law, enabling it to potentially reduce the amount of excise duty payable on its beer production.
What Is the Purpose of the APT3 Certificate?
The primary purpose of the APT3 certificate is to establish a brewery’s eligibility for alcohol products tax relief. Microbreweries that meet specific legal and operational criteria can apply for this certificate, which is then used to claim relief from excise duties on their beer production. This relief aims to support small-scale breweries by reducing their tax burden, encouraging growth and innovation within the Irish brewing sector.
By obtaining this certificate, breweries can demonstrate to the Revenue Commissioners that they operate as independent and compliant microbreweries, which is a prerequisite for accessing the relief. It also serves as an official record confirming their status and production details, which must be maintained for tax and regulatory purposes.
Who Can Apply for the APT3 Certificate?
The certificate is intended for breweries that meet the specific criteria outlined in Irish law, notably:
- Independence: The brewery must be an independent entity, physically separate from other breweries, and not under significant control or ownership by larger brewing companies.
- Production Volume: The brewery’s annual beer production must not exceed certain thresholds, typically less than 75,000 hectolitres for a single brewery or combined with other qualifying breweries.
- Operational Arrangements: The brewery should not be primarily operating under licensing, franchising, or contractual arrangements that would disqualify it from the relief.
Additionally, breweries that own multiple qualifying microbreweries can apply for a consolidated status, provided they meet the criteria for being considered a single independent brewery under the relevant legal definitions.
How to Obtain the APT3 Certificate
The process involves submitting a detailed application to the Irish Revenue Commissioners, including:
- Completing the Relevant Declarations: The application must include declarations confirming the brewery’s independence, production volumes, and operational arrangements. These are documented in specific sections of the form, such as the Declaration of Conformity and the Declaration of Annual Production.
- Providing Brewery Details: The application must include the brewery’s name, address (including Eircode), VAT number, and other relevant identifiers such as the Tax Warehouse Number.
- Signature and Certification: The declaration must be signed by the brewery warehousekeeper or an authorized person, affirming the accuracy of the information provided.
It is advisable for breweries to review the Administration & Control of Tax Warehouses manual, specifically Part 2 on breweries and microbreweries, before completing the application to ensure compliance with all legal requirements.
Validity and Usage of the Certificate
Once issued, the APT3 certificate confirms the brewery’s eligibility for alcohol products tax relief for a specified period, typically aligned with the tax year ending on 31 December. The brewery must retain this certificate and related documentation as proof of their qualification for tax relief during audits or inspections by Revenue.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
The certificate is used to claim relief when calculating excise duties owed on beer production. It must be presented or referenced in relevant tax filings and kept up to date should the brewery’s operational circumstances change, such as ownership, production volume, or operational arrangements.
Important Considerations
- Legal Compliance: Making false statements or falsifying documents related to the relief can lead to severe penalties, including fines or criminal charges.
- Record Keeping: Breweries should maintain detailed records of production, ownership, and operational arrangements to support their eligibility claims.
- Review and Renewal: The certificate may require renewal or reapplication if circumstances change or upon expiry, ensuring continuous compliance and eligibility for relief.
In summary, the APT3 certificate is a vital document for qualifying Irish microbreweries seeking to benefit from alcohol products tax relief. Proper understanding and adherence to the application process ensure legal compliance and support the sustainable growth of small-scale brewing enterprises in Ireland.