Understanding the Official Irish Form for DWT Exemption: A Guide for PRSA Administrators
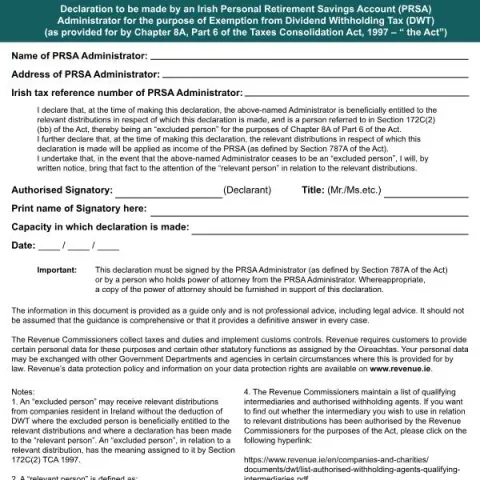
The Irish Revenue Commissioners require a specific declaration to be submitted by Personal Retirement Savings Account (PRSA) administrators to claim exemption from Dividend Withholding Tax (DWT). This form, identified by code RPC016550_EN_WB_L_1, plays a crucial role in ensuring that distributions made to certain beneficiaries are not subject to DWT, provided specific conditions are met. This article offers a comprehensive overview of this official form, its purpose, eligibility criteria, and the procedural steps involved in its completion and submission.
Purpose and Scope of the Form
This declaration form is designed for use by PRSA administrators who are beneficially entitled to distributions from Irish-resident companies or qualifying intermediaries. Its primary purpose is to establish that the administrator qualifies as an “excluded person” under Irish tax law, specifically Chapter 8A, Part 6 of the Taxes Consolidation Act, 1997. When correctly completed and submitted, the form enables the relevant distributions to be exempt from DWT, ensuring that pension fund assets are preserved and tax obligations are appropriately managed.
Who Should Complete the Declaration?
The form must be filled out by an authorized representative of the PRSA administrator, who holds beneficial entitlement to the relevant distributions. This includes:
- PRSA administrators themselves, acting on behalf of the pension scheme.
- Individuals or entities with power of attorney from the administrator, provided they submit supporting documentation such as a copy of the power of attorney.
It is important that the declarant is an “excluded person” as defined by Irish law, meaning they are entitled to the distributions without DWT deduction, subject to the declaration’s validity.
Key Conditions and Declarations
When completing the form, the declarant must affirm the following:
- They are beneficially entitled to the relevant distributions at the time of declaration.
- They qualify as an “excluded person” under Section 172C(2)(bb) of the Taxes Consolidation Act, 1997.
- The distributions will be applied as income of the PRSA, as per Section 787A of the Act.
- They undertake to notify the relevant person if their status changes and they cease to be an “excluded person.”
Step-by-Step Procedure for Filling Out the Form
1. Provide Administrative Details
Begin by entering the full name, address, and Irish tax reference number of the PRSA administrator. Accurate details ensure proper identification and processing of the declaration.
2. Confirm Beneficial Entitlement and Eligibility
Declare that, at the time of making the declaration, the administrator is beneficially entitled to the distributions and qualifies as an “excluded person.”
3. Signatory Declaration
The form must be signed by an authorized signatory, with their capacity clearly stated. The signatory must print their name, title, and date of signing.
4. Supporting Documentation
If the declaration is made by a person holding power of attorney, a copy of this authority should be attached to support the submission.
Submission and Post-Declaration Responsibilities
The completed declaration should be forwarded to the relevant person, which could be the Irish company making the distributions, a qualifying intermediary, or an authorized withholding agent, depending on the context. If the declaration is made via an intermediary or agent, it must be returned to them for onward submission.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
It is vital to retain a copy of the completed form for your records. Additionally, the administrator must notify the relevant person promptly if their status changes, such as ceasing to be an “excluded person,” to ensure ongoing compliance with Irish tax law.
Additional Information and Contact Details
The Revenue Commissioners maintain a list of authorized intermediaries and withholding agents. To verify whether an intermediary is authorized, consult the list available on the Revenue website. For further assistance, contact the DWT Section at +353 1 738 3631 or via email at [email protected].
In summary, this declaration form is a vital document for PRSA administrators seeking to benefit from exemption from DWT on relevant distributions. Proper completion and timely submission help ensure compliance with Irish tax legislation and the efficient management of pension assets.