Understanding the Declaration for Exemption from Dividend Withholding Tax (DWT) by Investment Limited Partnerships (ILPs) and Equivalent Partnerships (EP)
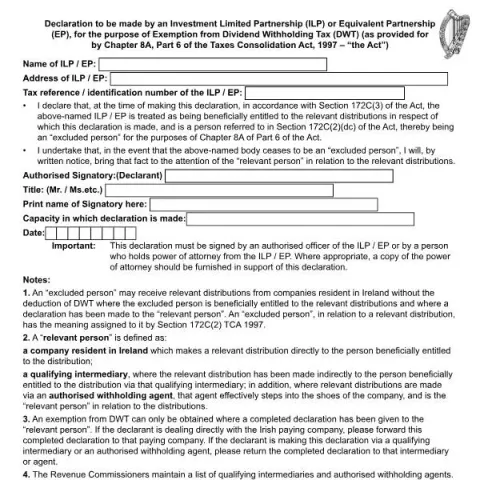
This official form, issued by the Revenue Commissioners of Ireland, is designed for Investment Limited Partnerships (ILPs) and Equivalent Partnerships (EPs) seeking exemption from Dividend Withholding Tax (DWT). The form, identified by code RPC020090_EN_WB_L_1, is a critical document in ensuring that eligible partnerships can benefit from tax relief provisions under Irish law, specifically Chapter 8A, Part 6 of the Taxes Consolidation Act, 1997.
Purpose of the Form
The primary objective of this declaration is to confirm the partnership's status as an “excluded person” eligible for exemption from DWT on relevant distributions received from Irish-resident companies. When correctly completed and submitted, this form prevents the deduction of DWT at source, facilitating the smooth receipt of distributions without withholding tax, provided the partnership meets the statutory criteria.
Who Should Complete This Declaration?
This form must be filled out by an authorized officer of the ILP or EP, or by a person holding power of attorney from the partnership. It is essential that the individual signing the form has the appropriate authority. In cases where a power of attorney is used, a copy of the legal documentation authorizing this power should be attached to the declaration.
How to Prepare and Submit the Declaration
Gathering Necessary Information
- Name of the Partnership: Provide the full official name of the ILP or EP.
- Address: Include the registered address of the partnership.
- Tax Reference Number: Enter the partnership’s tax identification number issued by Revenue.
Completing the Declaration
The declaration involves confirming that, as of the date of signing, the partnership is beneficially entitled to the relevant distributions and qualifies as an “excluded person” under Irish tax law. The signatory must declare their capacity, print their name, and date the form accordingly.
Submission Process
The completed declaration should be forwarded directly to the relevant Irish company or intermediary making the distributions. If the distribution is made via an authorized withholding agent or qualifying intermediary, the declaration should be sent to that entity. It is important to note that the Revenue Commissioners maintain a list of authorized agents; verifying this list can be done through their official publication.
Legal and Compliance Considerations
By signing this declaration, the signatory undertakes to notify the relevant person if the partnership ceases to qualify as an “excluded person.” This obligation ensures ongoing compliance with Irish tax regulations and prevents potential penalties or disallowance of the exemption.
Furthermore, the form must be signed by an authorized officer or a person with power of attorney, with supporting documentation provided where applicable. The declaration is valid only when fully completed and correctly signed.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Important Notes and Additional Guidance
- Exemption Eligibility: An “excluded person” is defined under Section 172C(2) of the Taxes Consolidation Act, 1997, and includes partnerships beneficially entitled to distributions from Irish-resident companies.
- Relevance of the Form: The exemption from DWT is only applicable if a completed declaration is submitted to the relevant Irish company or intermediary making the distribution.
- Verification of Intermediaries: To verify whether a qualifying intermediary or authorized withholding agent is approved by Revenue, consult the official list available online.
Contact and Further Assistance
For additional information or assistance with this declaration, contact the Revenue Commissioners’ DWT section at +353 1 738 3631 or via email at [email protected]. Detailed guidance and updates are also available on the Revenue website, including data protection policies related to the handling of personal information.
Adhering to these procedures ensures that ILPs and EPs can efficiently claim exemption from DWT, facilitating smooth financial operations and compliance with Irish tax law.