Understanding the VAT 72A Claim Form for Medical Research Equipment Refund in Ireland
The VAT 72A form is an official document issued by the Office of the Revenue Commissioners in Ireland. It serves as a formal application for claiming a refund of Value-Added Tax (VAT) paid on specific medical research equipment. This process is governed by the Value-Added Tax (Refund of Tax) (No. 27) Order, 1995, and is primarily aimed at qualifying research institutions and educational bodies involved in medical research activities.
Who Should Use the VAT 72A Form?
This form is intended for entities that have purchased medical research equipment costing €25,390 or more, on which VAT was paid. The applicant must be either the research institution or educational body that received the equipment via donation or the donor who paid the VAT. The equipment must be used exclusively for medical research purposes within a laboratory setting, and the claim must be made within four years from the end of the taxable period during which the VAT was paid.
Key Elements of the Claim Process
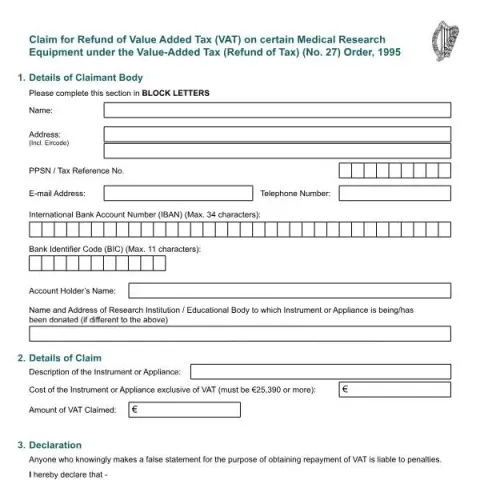
1. Completing the Claimant Details
The first section requires the applicant to provide comprehensive details, including:
- Name and Address: Write in BLOCK LETTERS, including the Eircode.
- PPSN or Tax Reference Number: Essential for identification and processing.
- Contact Information: Email and telephone number.
- Bank Details: IBAN, BIC, and account holder’s name for the refund transfer.
- Research Institution Details: If different from the claimant, include the name and address where the equipment is used or has been donated.
2. Providing Details of the Equipment and VAT
The second section focuses on the specifics of the medical research equipment:
- Description of the Instrument or Appliance: Clearly specify the nature of the equipment.
- Cost: The purchase price excluding VAT must be at least €25,390.
- VAT Amount Claimed: The amount of VAT paid and claimed back.
3. Declaration and Certification
The applicant must sign a declaration affirming:
- They are a qualifying body (e.g., research institution, university, or educational body).
- The equipment is used solely for medical research.
- No part of the purchase was funded by the State, public authorities, or other bodies associated with the research activity.
- The equipment is new and designed for research purposes.
- The Health Research Board has recommended the refund.
- VAT was paid on qualifying goods after 27 January 1994.
The declaration must be signed and dated, affirming the accuracy of all information provided.
Supporting Documentation and Submission
Before submitting the form, applicants should gather and attach the following:
- Original invoices or receipts showing VAT paid, including supplier details and VAT content.
- Supporting recommendation from the Health Research Board.
- Proof that the equipment cost exceeds the €25,390 threshold.
- Photocopies if originals are to be returned.
The completed form and supporting documents should be sent to:
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Collector-General’s Division, Office of the Revenue Commissioners, VAT Refund Schemes Section, Sarsfield House, Francis Street, Limerick, V94 R972.
Important Considerations and Points of Attention
- Eligibility: The equipment must be new, used exclusively for medical research, and the claim must be made within four years of the relevant taxable period.
- Donations: The claim process is based on the donation of equipment, and VAT can be reclaimed either by the donor or the recipient institution.
- Legal Compliance: Making false statements in the claim is liable to penalties under Irish law.
- Legal References: The process is governed by S.I. No. 38/1995, which details the conditions for VAT refunds on qualifying goods.
Additional Guidance
Applicants are advised to carefully review the notes provided by the Revenue Commissioners and ensure all sections are completed accurately. The form can be downloaded from the Revenue website or obtained directly from the Collector-General’s Division. Proper documentation and adherence to deadlines are crucial for successful processing of the refund claim.
By following these guidelines, eligible institutions can efficiently navigate the VAT refund process for medical research equipment, ensuring compliance with Irish taxation laws and supporting vital scientific research activities.