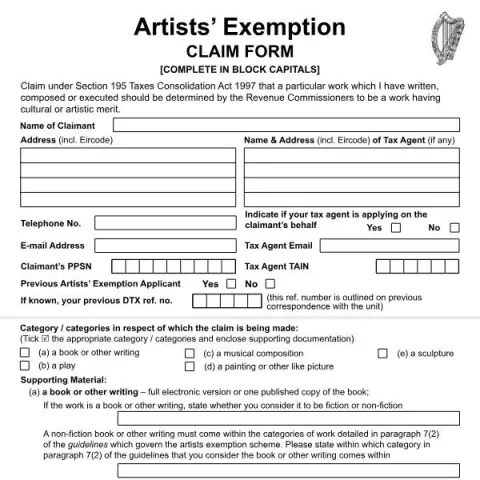
Understanding the Artists’ Exemption Claim Form in Ireland
The Artists’ Exemption Claim Form is an official document issued by the Revenue Commissioners of Ireland, designed to facilitate artists in claiming exemption from certain taxes on their works of cultural or artistic merit. This form is essential for eligible artists who wish to benefit from the Artists’ Exemption scheme under Section 195 of the Taxes Consolidation Act 1997. Below, we explore the purpose of the form, eligibility criteria, step-by-step instructions for filling it out, and important deadlines to keep in mind.
Purpose and Scope of the Form
The primary aim of the Artists’ Exemption Claim Form is to enable artists to formally declare that a specific work they have written, composed, or executed qualifies for tax exemption due to its cultural or artistic significance. By submitting this form, the artist requests that the Revenue Commissioners determine whether the work meets the necessary criteria for exemption. This process helps ensure that artists receive the appropriate tax relief on their qualifying works, which can include writings, plays, musical compositions, paintings, sculptures, or other artistic creations.
Eligibility Conditions for Making a Claim
To qualify for the Artists’ Exemption, applicants must meet specific residency and work-related criteria:
- The claimant must be resident, or ordinarily resident and domiciled, in Ireland, the European Union (EU), the European Economic Area (EEA), or the United Kingdom.
- The work in question must be of cultural or artistic merit, and the claim must be supported by appropriate documentation.
- Applicants who have previously claimed the exemption should provide their prior reference number to facilitate processing.
- The claim must be related to one or more of the following categories: writing (book, script), play, musical composition, painting, sculpture, or similar art forms.
Step-by-Step Guide to Completing the Form
1. Filling in Personal Details
Begin by providing your name, full address (including Eircode), and your Personal Public Service Number (PPSN). If you have a tax agent acting on your behalf, include their name, address, and contact details, and indicate whether they are applying on your behalf by ticking the appropriate box.
2. Providing Previous Claim Information
If you have previously applied for the Artists’ Exemption, include your previous reference number (DTX ref. no.) to assist the Revenue in processing your current claim.
3. Specifying the Category of Work
Tick the relevant box(es) to specify the category or categories of work for which you are claiming exemption. Supporting documentation must be enclosed, such as a script, photographs, or links to recordings, depending on the nature of the work:
- Writing: Full electronic version or published copy, with categorization as fiction or non-fiction.
- Play: Script and signed production contract.
- Musical Composition: Links, CD, or relevant recordings showing your accreditation.
- Painting or Picture: Six high-quality photographs and a brief CV.
- Sculpture: Similar supporting material as for paintings.
4. Declaration and Residence Details
Complete the declaration section by confirming your residency status and understanding the implications of the scheme. Answer questions about your country of residence, recent moves, and travel patterns to establish eligibility.
Submitting the Application
Applications can be submitted either by email to [email protected] or by post to:
Office of the Revenue Commissioners Artists’ Exemption Unit 1st Floor, Stamping Building Dublin Castle Dublin 2, D02 HW86, Ireland
For assistance, applicants may contact the Artists’ Exemption Unit via telephone or email, with contact details provided on the official Revenue website.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Important Deadlines and Follow-Up
The form must be submitted to Revenue to be considered for exemption. While the Revenue Commissioners do not specify a strict deadline for initial applications, it is advisable to submit well in advance of any planned sale or exhibition of the work. If the Revenue does not make a determination within a reasonable period, applicants have the right to appeal the decision to the Appeal Commissioners within six months and 30 days from the date of the original claim.
Post-Submission Considerations
If approved, the artist’s name and details of the work will be published on the Revenue website in accordance with the Freedom of Information Acts. It is essential to maintain residency and comply with the scheme’s residence requirements to retain exemption status. Any change in residence or circumstances should be promptly notified to Revenue, as non-compliance can result in withdrawal of the exemption and repayment of relief granted.
In summary, the Artists’ Exemption Claim Form is a vital document for Irish artists seeking tax relief on their culturally significant works. Proper completion and timely submission ensure that eligible artists can benefit from this valuable scheme while complying with Irish tax law and residency requirements.