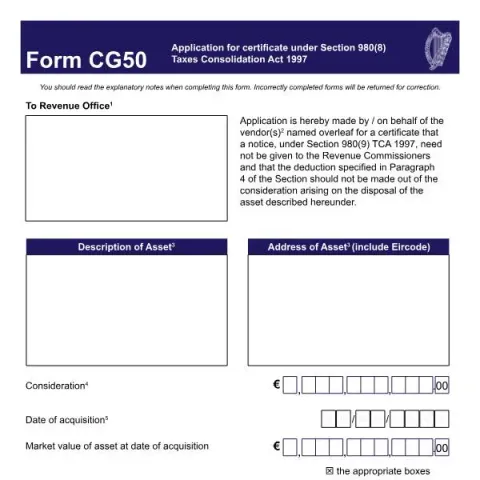
Understanding Form CG50: Application for a Certificate under Section 980(8) of the Taxes Consolidation Act 1997
Form CG50 is an official document issued by the Revenue Commissioners of Ireland, designed for individuals or entities involved in the disposal of assets, particularly land or property, to request a certificate that exempts them from giving notice under Section 980(9) of the Taxes Consolidation Act 1997. This form is essential for vendors seeking confirmation that certain tax obligations, such as Capital Gains Tax (CGT), will not be triggered or that specific deductions will not be applied at the point of disposal.
Purpose and Scope of Form CG50
The primary purpose of Form CG50 is to facilitate the application for a certificate that confirms the following:
- That the vendor is not required to give a notice of disposal to the Revenue Commissioners under Section 980(9).
- That the deduction specified in Paragraph 4 of Section 980(8) should not be made from the consideration arising from the disposal.
This process is particularly relevant when the vendor believes that no Capital Gains Tax is payable or that the specific circumstances of the disposal qualify for exemption. It provides legal assurance and clarity for both the vendor and the purchaser regarding tax obligations related to the transaction.
Who Should Complete and Submit the Form?
Form CG50 should be completed by the vendor or on behalf of the vendor involved in the disposal of an asset, such as land or property. It is crucial that the form is filled out accurately and comprehensively, including details of the asset, consideration, and parties involved. The completed form, along with a copy of the contract for sale, must be submitted to the Revenue Office responsible for the vendor's tax affairs.
In cases where the vendor is non-resident, the form should be sent directly to the Revenue Division handling non-resident tax matters, as outlined in the Tax and Duty Manual Part 42-03-01.
How to Complete Form CG50: Step-by-Step Guide
1. Details of the Vendor(s)
Provide the full name, address, and tax reference number of each vendor involved in the disposal. If more than four persons are involved, attach additional details on a separate sheet. For companies, include the registered office address.
2. Asset Description and Details
Describe the asset precisely, including its location and Eircode. For land or buildings, specify the address clearly. Indicate the date of acquisition and the market value at that time.
3. Consideration and Transaction Dates
State the total consideration passing on the disposal, including VAT if applicable. Also, provide the date of the contract for sale and the date of disposal, noting if the closing date has changed or if the consideration has not yet passed.
4. Details of the Purchaser(s)
Include the full name, address, and tax reference number of each purchaser. If multiple purchasers are involved, attach additional details as necessary. For trust arrangements, specify the actual purchaser rather than the trustee.
5. Vendor’s Declaration
The vendor must declare their residency status, whether any Capital Gains Tax is payable, and confirm that all previous tax obligations related to the asset have been settled. The declaration is signed and dated by the vendor or their authorized representative.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Important Considerations and Deadlines
Once completed, Form CG50 must be submitted promptly, ideally before the disposal is finalized. The Revenue Commissioners recommend submitting the form along with the contract of sale to ensure timely processing. If the vendor is resident in Ireland, the return of the disposal should be made by 31 October of the year following the disposal year. Payment of any applicable Capital Gains Tax, if due, is generally payable by 15 December for disposals made before 1 December, or by 31 January of the following year for disposals made after 1 December.
Post-Submission Procedures
After submission, the Revenue Commissioners review the application and, if satisfied, issue a certificate confirming that the notice under Section 980(9) is not required and that no deduction should be made. This certificate provides legal certainty and can be used to support the vendor’s position during tax audits or future transactions.
In summary, Form CG50 is a vital document for vendors seeking clarity and exemption from certain tax obligations related to asset disposals in Ireland. Accurate completion and timely submission are essential to ensure compliance and to facilitate smooth property transactions.