Understanding the Executive Regulation of Federal Law on Tax Procedures in the UAE
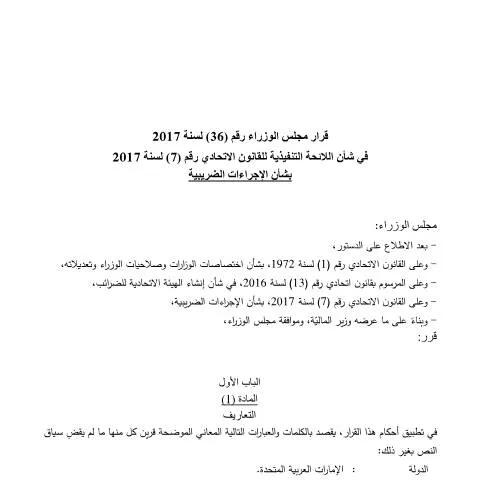
The Cabinet Decision No (36) of 2017, issued by the United Arab Emirates (UAE) government, constitutes a pivotal legal framework that complements Federal Law No (7) of 2017 concerning tax procedures. This regulation delineates the operational and procedural aspects of tax administration within the UAE, aiming to enhance compliance, streamline procedures, and reinforce the country's commitment to a transparent and efficient tax system. It is essential for businesses, tax practitioners, and government authorities to understand the scope and implications of this regulation to ensure adherence to the UAE's tax legislation.
Scope and Objectives of the Regulation
The executive regulation primarily aims to specify the detailed procedures and administrative mechanisms for implementing the provisions of the federal tax law. It applies across all emirates and covers various tax-related activities, including registration, filing, payment, and dispute resolution processes. The regulation seeks to facilitate a clear, predictable, and efficient tax environment that aligns with the UAE's broader objectives of economic diversification and global competitiveness.
Main Provisions and Key Administrative Procedures
Tax Registration and Registration Procedures
The regulation stipulates the criteria and procedures for registering for tax purposes, emphasizing the use of digital platforms provided by the Federal Tax Authority (FTA). Taxable persons are required to register via the FTA's online portal, where they obtain a unique taxpayer identification number. This digital process aims to simplify registration and ensure real-time processing, reducing administrative burdens on taxpayers.
Filing and Payment of Taxes
Taxpayers must adhere to specified timelines for submitting tax returns and making payments through the FTA's electronic systems. The regulation emphasizes the importance of timely compliance and provides detailed instructions on how to submit declarations, supporting documents, and payments through the official online channels. This digital-first approach enhances transparency and facilitates monitoring and enforcement by authorities.
Tax Audits and Dispute Resolution
The regulation outlines procedures for tax audits, including the rights and obligations of both tax authorities and taxpayers. It also establishes mechanisms for resolving disputes, encouraging dialogue and settlement through administrative channels before resorting to judicial proceedings. These provisions aim to ensure fairness and clarity in tax enforcement activities.
Implications for Taxpayers and Practitioners
Understanding and complying with the executive regulation is crucial for all entities engaged in economic activities within the UAE. It emphasizes the importance of digital compliance, urging taxpayers to utilize the FTA's online portals for registration, filing, and payments. This shift towards digital procedures not only aligns with the UAE's strategy for smart government services but also reduces the risk of non-compliance due to procedural errors.
Tax practitioners and advisors should familiarize themselves with the detailed procedures outlined in the regulation to assist their clients effectively. Moreover, the regulation's emphasis on transparency and dispute resolution mechanisms provides avenues for addressing issues amicably and efficiently, fostering a more predictable tax environment.
Conclusion
The Cabinet Decision No (36) of 2017 on the Executive Regulation of Federal Law No (7) of 2017 represents a significant step towards modernizing and clarifying the UAE's tax procedures. By establishing clear administrative processes and leveraging digital platforms, the regulation supports the country's vision of a transparent, efficient, and business-friendly tax system. Both taxpayers and tax professionals are encouraged to stay updated with these regulations to ensure full compliance and to benefit from the streamlined procedures introduced by this legal framework.