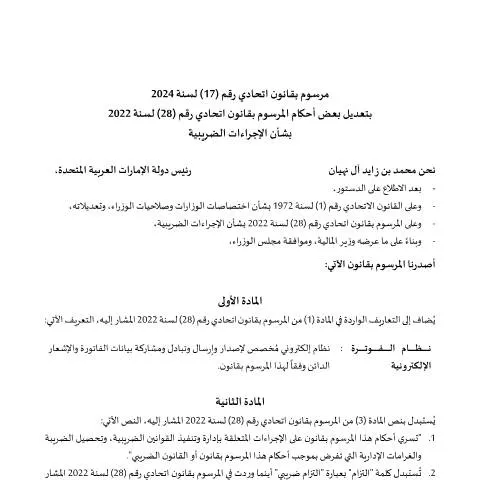
Overview of Federal Decree-Law No (17) of 2024: Amendments to UAE Tax Procedures
The United Arab Emirates has introduced a significant update to its tax legislation through the enactment of Federal Decree-Law No (17) of 2024. This decree amends certain provisions of the existing Federal Decree-Law No (28) of 2022 concerning tax procedures. Designed to enhance the efficiency, transparency, and compliance within the UAE’s tax system, these amendments aim to align with the country’s broader digital transformation and fiscal policies.
Scope and Purpose of the Amendments
The primary objective of Federal Decree-Law No (17) of 2024 is to refine the legal framework governing tax administration and compliance. It seeks to streamline procedures related to tax registration, declaration, and audit processes, while reinforcing the authority of the Federal Tax Authority (FTA) in enforcing tax laws. These amendments reflect the UAE’s commitment to maintaining a modern, transparent, and investor-friendly tax environment, consistent with its strategic vision for economic diversification and digital governance.
Who Is Affected by the New Provisions?
The amendments impact a broad spectrum of taxpayers operating within the UAE, including:
- Registered taxpayers under the Federal Decree-Law No (28) of 2022, including businesses and individuals involved in taxable activities.
- Tax agents and representatives responsible for managing tax affairs on behalf of clients.
- Tax authorities and officials tasked with enforcement, audit, and compliance activities.
The law emphasizes the importance of digital compliance mechanisms, which are increasingly integrated into the UAE’s tax administration processes. Consequently, taxpayers are encouraged to adapt to updated procedures and leverage digital platforms for their tax-related obligations.
Key Provisions and Changes Introduced
1. Enhanced Digital Reporting and Submission
The decree reinforces the use of the UAE’s digital tax portal, managed by the FTA, for submitting tax declarations, registration applications, and other related documents. It aims to facilitate faster processing times and reduce administrative burdens through automation and electronic workflows.
2. Clarification of Tax Audit Procedures
Amendments specify the scope and process of tax audits, including notification procedures and rights of taxpayers during audits. These provisions ensure transparency and fairness in enforcement actions, while allowing taxpayers to respond and rectify discrepancies efficiently.
3. Strengthening Taxpayer Rights and Obligations
The law emphasizes the importance of accurate record-keeping and timely submission of tax returns. It also delineates clearer procedures for disputes and appeals, reinforcing the rights of taxpayers to challenge assessments through formal channels.
4. Improved Enforcement and Penalty Regulations
New provisions streamline penalties for non-compliance, aligning them with international best practices. The amendments also specify procedures for the collection of overdue taxes and penalties, ensuring enforceability and legal clarity.
Legal References and Authority
The amendments are issued under the authority of the UAE Federal Constitution, which establishes the framework for federal laws and regulations. The Federal Tax Authority (FTA) remains the primary body responsible for implementing and overseeing tax legislation, ensuring compliance across all economic sectors.
Implications for Taxpayers and Stakeholders
Taxpayers should review their current compliance procedures to align with the updated provisions introduced by Federal Decree-Law No (17) of 2024. Embracing digital platforms and adhering to new audit and reporting standards will be crucial for maintaining compliance and avoiding penalties.
Furthermore, tax professionals and agents must stay informed about the evolving legal landscape to effectively advise clients and manage their tax obligations within the new legal framework.
References and Further Information
For detailed legal texts and official updates, stakeholders are advised to consult the UAE Federal Decree-Law No (17) of 2024, published through official channels such as the Federal Authority for Identity, Citizenship, Customs & Port Security (ICP), and the Federal Tax Authority (FTA). These bodies provide comprehensive guidance and digital resources to facilitate compliance and understanding of the amended tax procedures.