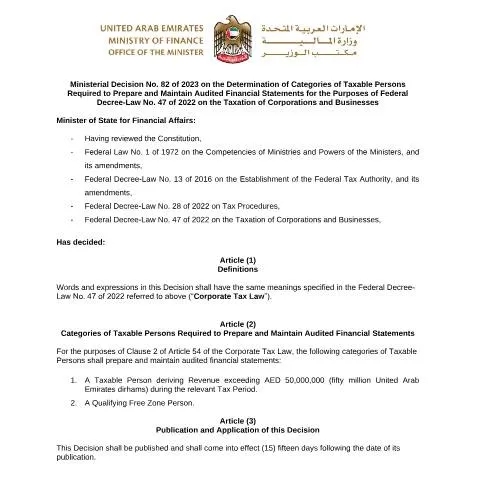
Overview of Ministerial Decision No (82) of 2023 on Taxable Persons and Financial Reporting Obligations in the UAE
The United Arab Emirates (UAE) continues to strengthen its fiscal transparency and corporate governance through the implementation of updated tax legislation. Central to this effort is the recent Ministerial Decision No (82) of 2023, which delineates the categories of taxable persons mandated to prepare and maintain audited financial statements in accordance with the provisions of Federal Decree-Law No (47) of 2022 on the taxation of corporations and businesses. This guide provides an overview of the decision’s scope, its implications for taxable entities, and the procedural framework established by the relevant authorities.
Scope and Purpose of the Decision
Ministerial Decision No (82) of 2023 aims to clarify the compliance obligations of different categories of taxable persons operating within the UAE’s federal tax system. It specifies which entities are required to prepare audited financial statements, ensuring adherence to international standards of financial transparency. This measure aligns with the UAE’s broader strategy to foster a robust tax environment, facilitate tax compliance, and promote fair competition among businesses.
The decision is part of the UAE’s ongoing efforts to implement the provisions of Federal Decree-Law No (47) of 2022, which introduced comprehensive corporate taxation regulations. By establishing clear criteria for financial reporting, the legislation aims to enhance the integrity of tax declarations, facilitate tax audits, and support the UAE’s reputation as a transparent and business-friendly jurisdiction.
Who Is Affected by This Decision?
The decision primarily targets taxable persons classified under the federal tax law, including but not limited to:
- Large corporations and companies operating in sectors such as finance, manufacturing, and trade that meet specific revenue or asset thresholds.
- Subsidiaries of foreign entities conducting business within the UAE and subject to corporate taxation.
- Partnerships and joint ventures that exceed certain operational parameters outlined by the legislation.
It is important for entities to assess their classification carefully, as the obligation to prepare audited financial statements is contingent upon their size, turnover, and other criteria specified by the authorities. Entities falling within these categories must ensure compliance with the reporting requirements to avoid penalties and facilitate smooth tax processes.
Key Provisions and Requirements
The decision stipulates that affected taxable persons are required to:
- Prepare audited financial statements in accordance with internationally recognized accounting standards.
- Maintain these financial statements for a prescribed period, ensuring their availability for review by tax authorities.
- Submit audited reports through the designated digital platforms, primarily via the UAE’s Federal Tax Authority (FTA) portal, ensuring timely compliance with filing deadlines.
Furthermore, the decision emphasizes the importance of maintaining accurate and complete financial records, which serve as the basis for tax declarations and audits. Entities are encouraged to leverage the digital infrastructure provided by the UAE government, including the use of the Emirates ID and the UAE Pass for secure access to online services.
Implementation and Compliance Framework
The Federal Tax Authority (FTA) is responsible for overseeing the implementation of this decision. It provides guidance and support to taxable persons to ensure their compliance with the new reporting obligations. The FTA’s digital platforms facilitate the submission of financial statements and related documentation, emphasizing the UAE’s commitment to a fully digitalized tax environment.
Taxable persons should regularly review updates from the FTA and consult with authorized tax advisors to ensure adherence to the latest legal requirements. The authorities may conduct audits and reviews based on the submitted financial statements, reinforcing the importance of accurate and timely reporting.
References and Further Guidance
For detailed information regarding the specific criteria, deadlines, and procedural steps, taxable persons are advised to consult official communications from the Federal Tax Authority and related regulatory bodies. The FTA’s official portal and the UAE government’s digital services platform serve as primary sources for guidance, updates, and submission procedures.
In conclusion, Ministerial Decision No (82) of 2023 underscores the UAE’s dedication to fostering a transparent, compliant, and efficient tax environment. Entities subject to these regulations should proactively review their financial reporting obligations and leverage the digital tools provided by the government to ensure full compliance with the evolving legal landscape.