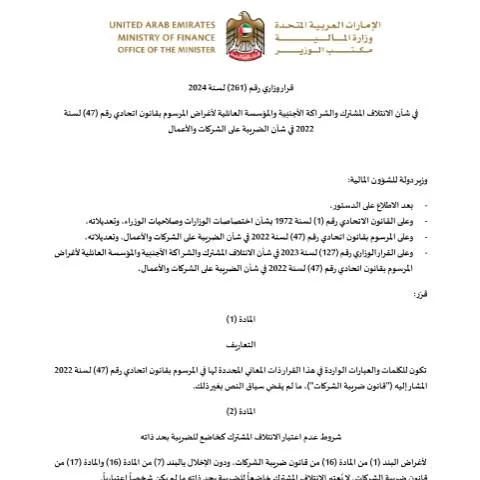
Understanding Ministerial Resolution No. 261 of 2024 on Joint Ventures, Foreign Partnerships, and Family-Owned Enterprises in the UAE
The recent issuance of Ministerial Resolution No. 261 of 2024 by the Federal Tax Authority (FTA) marks a significant development in the regulatory framework governing corporate structures for tax purposes within the United Arab Emirates. This resolution provides clarity on the classification and treatment of various business arrangements, including joint ventures, foreign partnerships, and family-owned enterprises, in alignment with Federal Law No. 47 of 2022 concerning corporate and business taxation.
Scope and Objectives of the Resolution
The primary objective of this ministerial resolution is to establish clear guidelines for the recognition and tax treatment of specific business entities that operate within the UAE’s legal and fiscal landscape. It aims to delineate the criteria under which joint ventures, foreign partnerships, and family enterprises are considered for tax purposes, ensuring consistency and compliance across different sectors and emirates.
Specifically, the resolution addresses the classification of these entities to facilitate accurate tax reporting, streamline registration procedures, and promote transparency in corporate operations. By doing so, it aligns with the broader strategic goal of the UAE to enhance its attractiveness as a business hub while maintaining robust tax governance.
Key Provisions and Definitions
Joint Ventures
The resolution defines a joint venture as a contractual arrangement where two or more parties collaborate to undertake a specific project or business activity, sharing profits, losses, and management responsibilities. It emphasizes the importance of clear contractual terms and the need for joint ventures to register with the relevant authorities for tax purposes.
Foreign Partnerships
Foreign partnerships are recognized as entities formed outside the UAE but conducting business within the country. The resolution stipulates that such partnerships must adhere to local registration requirements and comply with tax obligations, including the submission of relevant documentation to the Federal Tax Authority.
Family-Owned Enterprises
Family businesses, often structured as family holdings or private companies, are given specific recognition under this resolution. It highlights the importance of transparent ownership structures and proper documentation to ensure correct tax classification and to prevent tax evasion or misreporting.
Implications for Business Entities and Tax Compliance
This resolution clarifies the tax treatment of these entities, which can influence their reporting obligations and eligibility for certain tax incentives or exemptions. Entities classified under these categories are required to maintain accurate records, submit appropriate filings, and adhere to the UAE’s tax regulations as outlined by the Federal Law No. 47 of 2022.
Furthermore, the resolution encourages entities to utilize the digital platforms provided by the Federal Tax Authority for registration, filings, and communication, aligning with the UAE’s broader digital transformation initiatives. This approach aims to enhance efficiency, reduce administrative burdens, and ensure timely compliance.
What This Means for Business Owners and Investors
For entrepreneurs and investors operating or planning to establish businesses in the UAE, understanding the classifications introduced by this resolution is crucial. Proper categorization ensures accurate tax reporting, eligibility for incentives, and compliance with local regulations.
Business owners should review their current legal structures and consult with tax professionals or legal advisors to ensure alignment with the new provisions. Additionally, they should stay informed about ongoing updates from the Federal Tax Authority and other relevant authorities to maintain compliance and optimize their tax position.
Conclusion
The issuance of Ministerial Resolution No. 261 of 2024 reflects the UAE’s commitment to refining its corporate tax framework, promoting transparency, and supporting a conducive environment for diverse business models. By clearly defining the treatment of joint ventures, foreign partnerships, and family enterprises, the resolution aims to facilitate smoother business operations and reinforce the country’s reputation as a strategic and compliant business hub.
Businesses and investors are encouraged to stay updated with official communications from the Federal Tax Authority and seek professional guidance to navigate the evolving tax landscape effectively.