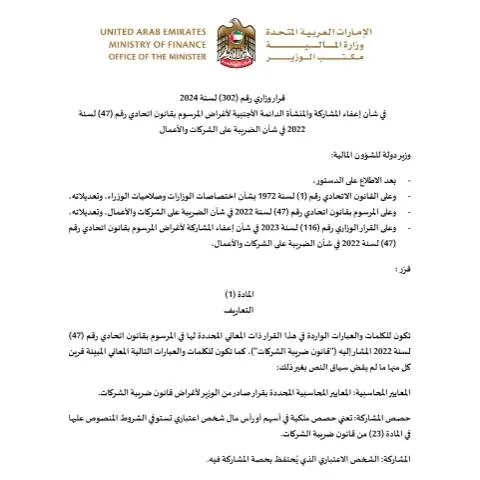
Understanding Ministerial Decision No. 302 of 2024 on Participation and Foreign Permanent Establishment Exemptions in the UAE
The United Arab Emirates (UAE) continuously evolves its tax legislative framework to promote economic growth and attract foreign investment. A significant development in this regard is the issuance of Ministerial Decision No. 302 of 2024, which addresses specific exemptions related to participation and foreign permanent establishments under the federal corporate tax law.
Context and Scope of the Decision
This ministerial decision is issued in the context of implementing the provisions of Federal Decree-Law No. 47 of 2022 concerning the Corporate Tax Law. Its primary purpose is to clarify and specify the conditions under which certain entities, specifically foreign participation entities and foreign permanent establishments, can benefit from tax exemptions. These exemptions aim to foster international business operations within the UAE, aligning with the country’s strategic goal of becoming a global hub for commerce and finance.
The decision applies to all relevant entities operating within the UAE’s federal tax framework, regardless of their location or nationality, provided they meet the eligibility criteria outlined in the law and this specific decision.
Who Is Affected by This Decision?
- Foreign Participation Entities: Companies or entities that hold a participation stake in UAE-based businesses or projects, whether through direct ownership or indirect arrangements.
- Foreign Permanent Establishments (PEs): Branches or offices of foreign companies that operate within the UAE, conducting business activities on behalf of their parent companies.
These entities, if qualifying under the conditions set forth in the decision, may benefit from exemptions that reduce their tax liabilities, thus encouraging foreign direct investment and operational expansion within the country.
Key Provisions and Points of the Decision
Participation Exemption
The decision stipulates that qualifying foreign participation entities may be exempt from certain corporate tax obligations on income derived from their participation in UAE companies. This exemption is designed to prevent double taxation and promote cross-border investments.
Foreign Permanent Establishment Exemption
For foreign PEs operating in the UAE, the decision provides specific criteria under which income attributable to these establishments can be exempt from UAE corporate tax. This aims to facilitate international business activities by alleviating tax burdens on foreign companies' UAE operations.
Conditions for Eligibility
- The entity must meet the definitions and criteria outlined in the federal tax law concerning foreign participation and PEs.
- The exemption is granted based on compliance with reporting, documentation, and operational requirements established by the Federal Tax Authority (FTA).
- Entities must ensure proper registration and adherence to the procedures stipulated by the relevant authorities to qualify for these exemptions.
Implementation and Compliance
Entities seeking to benefit from these exemptions should maintain comprehensive records and documentation demonstrating their eligibility. They are advised to consult with tax professionals or legal advisors specializing in UAE corporate tax law to ensure full compliance with the requirements.
The Federal Tax Authority (FTA) oversees the implementation of these provisions and provides guidance on application procedures and necessary documentation. Entities are encouraged to utilize the digital portals provided by the FTA and other relevant authorities to manage their exemption claims efficiently.
References and Regulatory Framework
This decision complements the broader legal and regulatory framework established by the UAE federal government, including the provisions of the UAE Constitution, the Corporate Tax Law, and related executive regulations. All entities operating within the UAE should stay informed of updates from the FTA and other relevant authorities to ensure ongoing compliance and optimal benefit from available exemptions.
For detailed legal interpretation and application procedures, entities are advised to consult the official publications and guidance issued by the Federal Tax Authority and the Ministry of Finance (MOF).