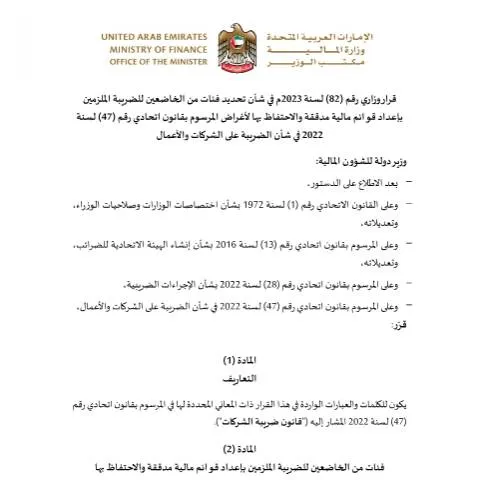
Understanding the Ministerial Decision No. 82 of 2023 on Taxable Entities and Financial Reporting Requirements in the UAE
The United Arab Emirates (UAE) continues to enhance its tax framework to promote transparency, compliance, and fiscal responsibility among business entities operating within its jurisdiction. A key development in this regard is the issuance of Ministerial Decision No. 82 of 2023, which delineates specific categories of taxable persons mandated to prepare and maintain audited financial statements, in accordance with the provisions of Federal Decree-Law No. 47 of 2022 concerning corporate and business taxation.
Scope and Purpose of the Decision
This ministerial decision aims to clarify the obligations of various classes of taxpayers regarding their financial reporting duties. It specifies which entities are required to prepare audited financial statements and retain them for a designated period. The overarching goal is to align tax compliance with international standards of financial transparency and to facilitate effective tax administration by the Federal Tax Authority (FTA).
The decision complements existing legal frameworks by providing detailed criteria that determine the scope of entities subject to these financial documentation obligations. It underscores the UAE’s commitment to fostering a business environment grounded in accountability, supported by a modern, digitally integrated tax system.
Entities Affected by the Decision
The decision targets a broad spectrum of taxable persons, including but not limited to:
- Large corporations and companies operating in sectors with significant economic impact.
- Partnerships and sole proprietorships exceeding specific turnover or asset thresholds.
- Foreign entities with a permanent establishment within the UAE.
- Other business entities designated by the FTA based on their size, turnover, or sector.
It is important to note that the criteria for classification are based on parameters such as turnover, total assets, and the nature of business activities, which are detailed in the official guidance provided by the FTA and relevant authorities.
Key Obligations for Taxable Persons
Taxable entities falling under the scope of this decision are required to:
- Prepare comprehensive, audited financial statements in accordance with applicable accounting standards.
- Retain these financial statements for a minimum period specified by the FTA, ensuring their availability for review or audit purposes.
- Submit financial reports as part of their tax filings through the designated digital platforms provided by the UAE government, primarily via the FTA portal.
The emphasis on digital submission aligns with the UAE’s broader strategy to digitize government services, reduce paper-based processes, and improve efficiency in tax administration.
Implementation and Compliance
Entities affected by this decision should review their existing financial reporting practices to ensure compliance. The FTA offers comprehensive guidance and support to facilitate the transition, including detailed instructions on the format, content, and submission procedures for audited financial statements.
Failure to comply with these requirements may result in penalties, audits, or other administrative measures as stipulated under the applicable tax laws and regulations.
References and Further Guidance
For detailed information on the specific criteria, deadlines, and procedures related to this decision, taxable persons are advised to consult the official publications and guidance issued by the Federal Tax Authority (FTA). The FTA’s digital platforms and official website serve as primary sources for updates, forms, and procedural instructions.
This decision exemplifies the UAE’s ongoing efforts to strengthen its fiscal framework through clear legal obligations and advanced digital infrastructure, ensuring a compliant and transparent business environment.