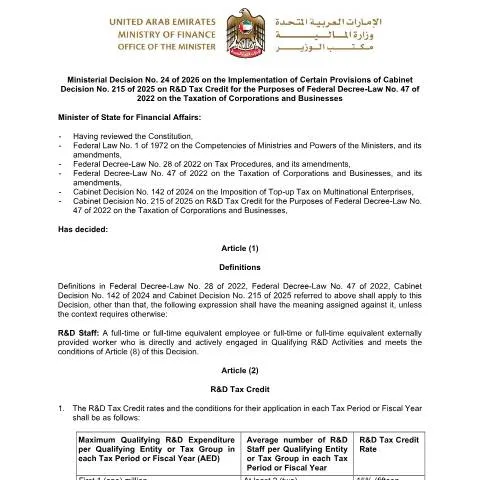
Overview of Ministerial Decision No. 24 of 2026 on R&D Tax Credit Implementation
The United Arab Emirates (UAE) continues to strengthen its commitment to fostering innovation and technological advancement through targeted fiscal policies. Ministerial Decision No. 24 of 2026, issued by the Ministry of Finance, serves as a crucial regulatory instrument that operationalizes specific provisions of Cabinet Decision No. 215 of 2025 concerning the Research & Development (R&D) Tax Credit. This decision aims to encourage businesses and research entities to invest more actively in innovative activities by providing fiscal incentives aligned with national economic diversification goals.
Scope and Objectives of the Decision
The primary purpose of Ministerial Decision No. 24 of 2026 is to establish clear guidelines for the application and administration of R&D tax credits within the UAE's tax framework. It delineates the procedures for claiming eligible R&D expenses, defines qualifying activities, and sets out compliance requirements for corporate taxpayers seeking to benefit from these incentives. The decision underscores the UAE’s strategic move to position itself as a regional hub for innovation by reducing the financial barriers faced by research-intensive industries.
Who Is Affected by This Decision?
This regulation primarily targets corporate entities engaged in research and development activities across various sectors, including technology, healthcare, engineering, and scientific research. Taxpayers registered with the Federal Tax Authority (FTA) that conduct qualifying R&D projects are eligible to apply for the tax credits. Additionally, research institutions and innovation-focused startups that meet the criteria outlined in the decision may also benefit from these incentives, provided they comply with the stipulated documentation and reporting standards.
Key Provisions and Implementation Guidelines
Qualifying R&D Activities
- Activities aimed at developing new or improved products, processes, or services.
- Research conducted to generate new scientific or technical knowledge.
- Development activities that involve experimental or systematic work to solve technological uncertainties.
Eligible Expenses
The decision specifies that expenses directly related to R&D projects, such as personnel costs, laboratory materials, equipment depreciation, and outsourced research services, may qualify for the tax credit. It emphasizes the importance of maintaining detailed records and supporting documentation to substantiate claims.
Application and Compliance Process
- Submission of a detailed R&D project report through the designated digital portal of the Federal Tax Authority.
- Provision of supporting documentation demonstrating the eligibility of expenses and activities.
- Periodic reporting and audits to ensure ongoing compliance with the criteria outlined in the decision.
References and Regulatory Framework
Ministerial Decision No. 24 of 2026 is part of the broader legislative framework aimed at promoting innovation through fiscal policy. It complements the provisions of Cabinet Decision No. 215 of 2025, which established the general principles of the R&D tax credit scheme. The implementation and enforcement of this decision are overseen by the Federal Ministry of Finance, working closely with the Federal Tax Authority (FTA) and other relevant authorities.
Conclusion
The issuance of Ministerial Decision No. 24 of 2026 marks a significant step in the UAE’s strategic effort to cultivate a knowledge-based economy. By clarifying the operational aspects of the R&D tax credit, the decision provides a transparent and efficient pathway for eligible entities to benefit from fiscal incentives. Entities involved in research and innovation are encouraged to familiarize themselves with these guidelines and ensure compliance to leverage the available benefits fully.