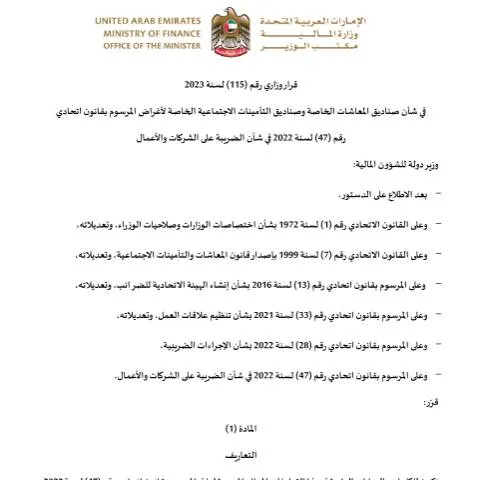
Overview of Ministerial Decision No. (115) of 2023 on Private Pension Funds and Private Social Insurance Funds for Corporate Tax Purposes
The United Arab Emirates (UAE) continues to refine its legal framework concerning corporate taxation and related financial arrangements. A recent ministerial decision, numbered (115) of 2023, issued by the Ministry of Finance, specifically addresses the treatment of private pension funds and social insurance funds within the context of the country's corporate tax legislation. This guidance aims to clarify the regulatory stance and provide a structured approach for entities managing such funds under the provisions of Federal Decree-Law No. (47) of 2022 on Corporate Tax.
Scope and Object of the Decision
The primary objective of Ministerial Decision (115) of 2023 is to establish clear guidelines regarding the classification, tax treatment, and compliance obligations of private pension funds and private social insurance funds operating within the UAE. These funds are recognized as essential components of employee benefit schemes and social security arrangements. The decision delineates the conditions under which these funds are considered separate legal entities and how they should be integrated into the corporate tax framework.
Furthermore, the decision aims to facilitate transparency and consistency in the tax treatment of such funds, ensuring that companies and fund managers adhere to the applicable legal standards while optimizing their tax positions within the bounds of the law.
Scope of Application
This decision applies to all private pension funds and social insurance funds established and operated by companies, whether local or foreign, that generate income subject to UAE corporate tax. It covers funds set up for the purpose of providing retirement benefits, social security, or other employee-related social benefits, provided they are managed as separate legal entities or through contractual arrangements recognized under UAE law.
It is pertinent to note that the decision emphasizes the importance of proper registration and compliance with the relevant authorities, such as the Federal Tax Authority (FTA), the Ministry of Human Resources and Emiratization, and other relevant entities involved in the oversight of employee benefit schemes.
Key Provisions and Regulatory Guidance
Classification and Recognition
- Private pension funds and social insurance funds are to be recognized as distinct entities that may be subject to specific tax treatment depending on their structure and operations.
- Funds that qualify as separate legal entities are encouraged to register with the relevant authorities to ensure compliance and proper tax reporting.
Tax Treatment and Deductions
- The decision provides guidance on the deductibility of contributions made by employers and employees to these funds, aligning with the provisions of the overarching corporate tax law.
- It clarifies the circumstances under which the income generated by these funds may be exempt from corporate tax or subject to specific exemptions, subject to compliance with legal requirements.
Reporting and Compliance
- Entities managing private pension and social insurance funds must maintain accurate records and submit regular reports to the relevant authorities, ensuring transparency and accountability.
- Proper documentation and adherence to registration procedures are emphasized to avoid penalties and ensure legal compliance.
Implications for Employers and Fund Managers
This decision signifies a move toward greater clarity and regulation of employee benefit schemes within the UAE's evolving tax landscape. Employers and fund managers should review their current arrangements to ensure they meet the new regulatory standards. Proper registration, documentation, and adherence to reporting obligations will be essential to benefit from the intended tax treatments and avoid potential legal issues.
Additionally, the decision underscores the importance of aligning internal policies with federal and emirate-level regulations, particularly regarding the management and taxation of these funds.
Conclusion
Ministerial Decision No. (115) of 2023 plays a crucial role in shaping the regulatory environment for private pension and social insurance funds in the UAE. It aims to promote transparency, compliance, and fiscal discipline among entities managing these funds, aligning with the broader objectives of the UAE's tax reforms under Federal Decree-Law No. (47) of 2022. Stakeholders involved in employee benefits and social security arrangements should stay informed about these guidelines to ensure their operations are compliant with the latest legal standards.