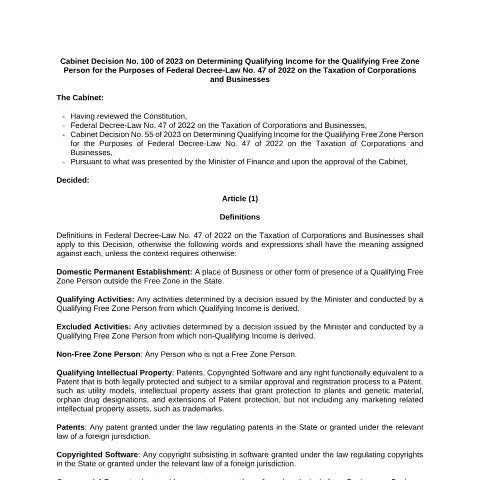
Overview of Cabinet Decision No (100) of 2023 on Qualifying Income for Free Zone Entities
The United Arab Emirates continues to refine its tax framework to promote economic growth and clarify the fiscal responsibilities of various business entities. A significant development in this regard is the issuance of Cabinet Decision No (100) of 2023, which establishes the criteria for determining the Qualifying Income for entities operating within Free Zones, as aligned with the provisions of Federal Decree-Law No (47) of 2022 on the taxation of corporations and businesses.
Context and Scope of the Decision
This decision is part of the UAE’s broader strategy to create a transparent and predictable tax environment, especially for businesses operating in Free Zones, which are key drivers of the national economy. It aims to define the parameters under which Free Zone persons (entities or individuals) can qualify for specific tax treatments, including exemptions and incentives, under the new federal corporate tax regime.
The decision applies to all Free Zone entities that are subject to federal corporate tax laws and seeks to harmonize tax compliance across different jurisdictions within the UAE. It emphasizes the importance of clear criteria for income classification to facilitate compliance and foster a business-friendly environment.
Who Is Affected by the Decision?
The primary beneficiaries of this decision are entities registered within designated Free Zones that are engaged in commercial, industrial, or service activities. These include:
- Free Zone companies and branches
- Partnerships and sole proprietorships with operations in Free Zones
- Specialized Free Zone entities involved in sectors such as finance, logistics, and technology
It also impacts tax authorities and regulatory bodies responsible for overseeing compliance and ensuring that entities correctly determine their qualifying income in accordance with federal regulations.
Key Principles and Criteria
The decision delineates the concept of Qualifying Income as the income derived from activities that meet specific conditions set forth by the federal tax law. While the detailed thresholds and calculations are governed by the implementing regulations, the main principles include:
- The income must be generated from activities conducted within the scope of the Free Zone’s designated economic activities.
- Income derived from outside activities or jurisdictions generally does not qualify unless explicitly permitted by the law.
- Entities must maintain proper documentation and records to substantiate the origin and nature of their income.
- The determination of qualifying income is subject to periodic review by tax authorities to ensure ongoing compliance.
The decision also highlights the importance of aligning income classification with the UAE’s overarching tax policy, aiming to prevent tax evasion and promote fair taxation practices.
Implementation and Compliance
Entities operating within the Free Zones are encouraged to review their income streams and ensure proper categorization under the new criteria. Compliance involves maintaining detailed financial records, supporting documentation, and adherence to reporting obligations mandated by the Federal Tax Authority (FTA).
Taxpayers should also consult the relevant regulatory bodies for guidance on how to accurately determine and report their qualifying income, especially as the definitions and thresholds may evolve with further regulations and clarifications issued by the FTA.
References and Regulatory Framework
This decision complements other legal instruments and guidelines issued by the UAE government to streamline the taxation process and clarify the scope of taxable income for Free Zone entities. It is part of the UAE’s ongoing efforts to foster a transparent, efficient, and compliant tax environment.
For comprehensive guidance and updates, entities and stakeholders are advised to refer to official communications from the Federal Decree-Law No (47) of 2022 and consult with the Federal Tax Authority (FTA) and relevant Free Zone authorities.