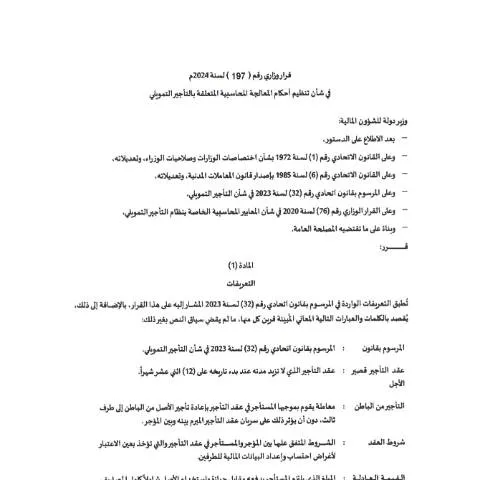
Understanding the Ministerial Decision No (197) of 2024 on Financial Leasing Accounting Regulation in the UAE
The United Arab Emirates continues to strengthen its financial sector through the implementation of comprehensive regulatory frameworks. The recent Ministerial Decision No (197) of 2024, issued by the relevant authorities, introduces significant updates concerning the accounting treatment within the financial leasing sector. This guide aims to clarify the scope, key provisions, and implications of this decision for stakeholders involved in financial leasing activities across the UAE.
Objective and Scope of the Decision
The primary aim of Ministerial Decision No (197) of 2024 is to establish standardized accounting practices for entities engaged in financial leasing operations. It seeks to ensure consistency, transparency, and compliance with the overarching legal and regulatory environment mandated by the UAE authorities. This decision applies to all financial leasing companies operating within the UAE, including those licensed at both federal and emirate levels, and covers all types of leasing transactions classified under the financial leasing system.
It is important to note that the regulation aligns with the UAE's broader financial sector policies, emphasizing digital compliance and adherence to international accounting standards, adapted to the local legal context.
Key Provisions and Regulatory Framework
Standardization of Accounting Treatments
- The decision mandates specific accounting procedures for recognizing, measuring, and disclosing financial leasing transactions. It emphasizes the importance of accurately reflecting leasing assets, liabilities, and income in financial statements.
- Entities are required to adopt a consistent approach in applying the principles outlined, ensuring comparability and clarity in financial reporting.
Recognition and Measurement
- Leasing assets must be recognized on the lessee's and lessor's balance sheets according to the prescribed guidelines, which align with international standards but are tailored for the UAE market.
- Measurement of lease liabilities and assets must consider the lease term, interest rates, and other relevant contractual terms, with specific instructions provided for different types of leases.
Disclosure Requirements
- Financial leasing entities are obliged to disclose detailed information about their leasing portfolios, including lease terms, residual values, and associated risks, in their financial statements.
- Transparency is reinforced through mandatory notes and disclosures that facilitate stakeholder understanding and regulatory oversight.
Implications for Financial Leasing Stakeholders
The implementation of this decision represents a significant step toward harmonizing accounting practices within the UAE’s financial leasing sector. For leasing companies, this entails reviewing and potentially revising existing accounting policies to ensure compliance with the new standards. It also emphasizes the importance of robust internal controls and accurate record-keeping to meet disclosure obligations.
For auditors and regulatory bodies, the decision provides clear benchmarks for assessing the accuracy and completeness of financial reports related to leasing activities. It enhances the overall integrity of financial data, supporting the UAE’s commitment to a transparent and resilient financial system.
Digital Compliance and Future Outlook
Aligned with the UAE’s strategic focus on digital transformation, the regulation encourages the use of digital tools and platforms to facilitate compliance. Financial leasing entities are expected to leverage the digital infrastructure provided by federal and emirate authorities, such as the UAE Pass and integrated reporting systems, to streamline their reporting processes.
Looking ahead, the decision underscores the UAE’s ongoing efforts to update and refine its financial regulatory landscape, ensuring it remains aligned with international best practices while accommodating local legal and economic contexts. Stakeholders are advised to stay informed about further updates and to seek guidance from relevant authorities to ensure seamless compliance.
Conclusion
Ministerial Decision No (197) of 2024 marks a pivotal development in the regulation of financial leasing accounting in the UAE. By establishing clear standards and promoting transparency, it aims to bolster confidence among investors, regulators, and market participants. Entities engaged in financial leasing should review their accounting policies and systems accordingly to align with these new requirements, thereby contributing to the stability and growth of the UAE’s financial sector.