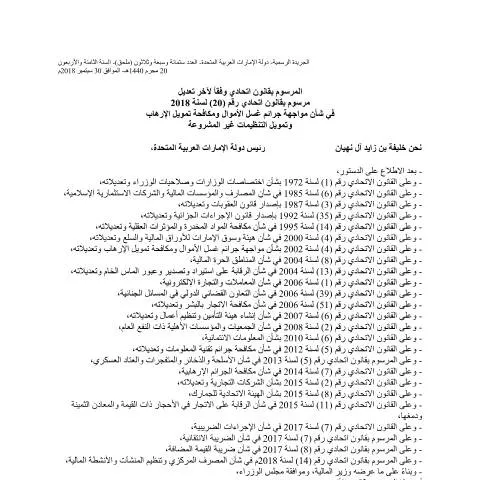
Understanding the Federal Decree-Law No (20) of 2018 on Anti-Money Laundering and Combating the Financing of Terrorism and Illegal Organisations in the UAE
The United Arab Emirates (UAE) has established a comprehensive legal framework aimed at strengthening its financial sector’s integrity and preventing illicit activities such as money laundering and terrorism financing. Central to this effort is the Federal Decree-Law No (20) of 2018, which sets out the legal obligations and procedures for financial institutions and related entities operating within the country. This guide provides an overview of the law’s scope, key provisions, and implications for stakeholders, emphasizing the importance of compliance within the UAE’s robust, digitally driven regulatory environment.
Scope and Application of the Law
The law applies broadly to all financial institutions and activities within the UAE, including banks, insurance companies, exchange houses, and other entities involved in financial transactions. It also covers designated non-financial businesses and professions (DNFBPs), such as real estate agencies, legal and accounting firms, and precious metals traders, which may be used to facilitate money laundering or terrorism financing.
In line with the UAE’s commitment to international standards, the law mandates these entities to implement effective measures to identify, assess, and mitigate risks related to money laundering and terrorist financing. The law’s digital orientation ensures that compliance processes are integrated into the UAE’s national digital infrastructure, including the use of the Emirates ID and UAE Pass for identity verification and reporting.
Main Provisions and Obligations
Customer Due Diligence and Know Your Customer (KYC)
Financial institutions are required to perform thorough customer due diligence (CDD) procedures before establishing a business relationship. This includes verifying the identity of clients using official identification documents, such as the Emirates ID or passport, and understanding the nature and purpose of the business relationship. Enhanced due diligence is mandated for high-risk clients or transactions.
Reporting Suspicious Activities
Entities must establish internal controls and reporting mechanisms to detect and report suspicious transactions or activities that may be linked to money laundering or terrorism financing. Reports are submitted electronically to the UAE Financial Intelligence Unit (FIU), ensuring swift and secure communication within the digital framework of the UAE’s financial oversight system.
Record-Keeping and Data Management
All relevant transaction records, customer identification data, and internal compliance reports must be maintained securely for a specified period. These records are crucial for audits and investigations and are managed through secure digital systems aligned with the UAE’s e-government services.
Implications for Financial Entities and Professionals
Compliance with the Federal Decree-Law No (20) of 2018 is mandatory for all covered entities, with non-compliance potentially resulting in penalties, license suspension, or other legal consequences. The law emphasizes the importance of integrating anti-money laundering (AML) and counter-terrorism financing (CTF) measures into daily operations, leveraging the UAE’s digital infrastructure for efficient compliance management.
Financial institutions are encouraged to develop comprehensive AML/CTF policies, conduct regular staff training, and utilize advanced digital tools to monitor transactions effectively. The UAE’s regulatory authorities provide guidance and support to ensure that entities stay aligned with legal requirements and international best practices.
Conclusion: Navigating Compliance in a Digital Era
The Federal Decree-Law No (20) of 2018 reflects the UAE’s strategic approach to safeguarding its financial system against illicit activities through a combination of legal rigor and digital innovation. For financial institutions and related entities, understanding and implementing the law’s provisions is essential not only for legal compliance but also for maintaining trust and integrity within the UAE’s dynamic economy.
As the UAE continues to enhance its digital infrastructure, entities should stay informed about updates and best practices to ensure their compliance frameworks remain robust and effective. This proactive approach will support the UAE’s broader goal of fostering a transparent, resilient, and internationally compliant financial environment.