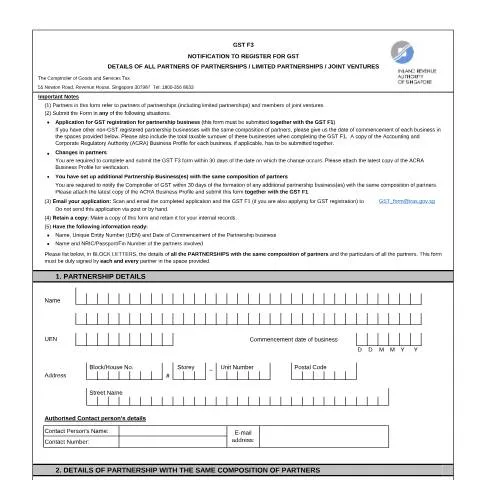
Understanding the IRAS GST F3 Form: Registration and Deregistration of Partnership Businesses
The GST F3 form, issued by the Inland Revenue Authority of Singapore (IRAS), is a crucial document for partnership businesses involved in Goods and Services Tax (GST) registration or deregistration. This form facilitates the process of updating the IRAS on changes related to partnerships, including new registrations, changes in partners, or the setup of additional partnership businesses with the same composition of partners. It is part of Singapore's comprehensive GST management system, ensuring that the tax records are accurate and up-to-date.
Purpose and Scope of the GST F3 Form
The primary purpose of the GST F3 form is to notify IRAS of:
- Application for GST registration for a partnership business
- Changes in the partnership's composition, such as addition or removal of partners
- Establishment of additional partnership businesses with the same partners
This form is essential for partnerships that are already registered for GST or are in the process of registering, especially when there are significant changes affecting their registration status. Submitting accurate and timely information helps ensure compliance with Singapore's GST regulations and facilitates proper tax administration.
Who Should Use the GST F3 Form?
The GST F3 form is intended for partnership entities, including limited partnerships and joint ventures, that need to notify IRAS about changes affecting their GST registration. The form is particularly relevant in the following situations:
- When applying for GST registration as a partnership
- When there are changes in the partnership's partners, such as new partners joining or existing partners leaving
- When establishing additional partnership businesses with the same partnership composition
It is important to note that the form must be submitted within 30 days of the change occurring, to ensure compliance with IRAS regulations.
Key Information Required for Completing the GST F3 Form
Preparing the GST F3 form requires gathering specific details about the partnership and its partners. The main information includes:
- Partnership details: Name, Unique Entity Number (UEN), and date of commencement
- Partnership address: Block, house number, storey, unit number, postal code, and street name
- Authorised contact person: Name and contact number
- Details of all partners: Full name, NRIC/Passport/Fin Number, address, and email
- UEN of any other partnership businesses with the same partners and their respective commencement dates
It is advisable to have copies of the latest ACRA Business Profile for each relevant partnership business, as these documents may need to be attached during submission.
Step-by-Step Procedure for Filling Out the GST F3 Form
- Gather necessary information: Ensure you have all partnership and partner details ready, including UENs and commencement dates.
- Complete the form electronically: Fill out the GST F3 form via the official digital platform, ensuring accuracy and completeness.
- Attach supporting documents: Scan and attach the latest ACRA Business Profile for verification purposes.
- Sign the form: Each partner involved must sign the form to certify the accuracy of the information provided.
- Submit via email: Send the completed form and any supporting documents to IRAS at [email protected].
Important Deadlines and Post-Submission Actions
It is mandatory to submit the GST F3 form within 30 days of the occurrence of any change affecting the partnership's GST registration status. Failure to do so may result in penalties or non-compliance issues.
After submission, IRAS will review the information and update their records accordingly. It is recommended to retain a copy of the submitted form and supporting documents for internal records and future reference.
Additional Considerations
Partnerships should ensure that all partners sign the form, as their signatures certify the accuracy and authenticity of the information. Changes in partnership composition should be promptly reported to avoid discrepancies in GST filings and tax obligations.
For further assistance or clarification, partners can contact IRAS directly via the provided telephone number or consult the official IRAS website for detailed guidance on GST registration and deregistration procedures.