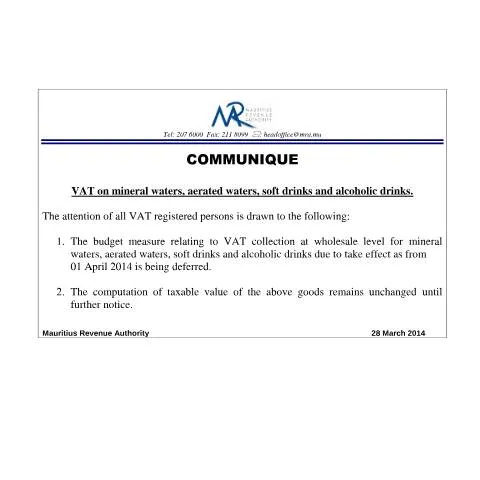
Official Notice on VAT Regulations for Specific Goods in Mauritius
Introduction and Purpose of the Notice
This official communication from the Mauritius Revenue Authority (MRA) serves to inform VAT-registered persons about recent developments concerning the application of Value Added Tax (VAT) on certain categories of goods, namely mineral waters, aerated waters, soft drinks, and alcoholic beverages. The notice, issued on 28 March 2014, clarifies the status of planned changes to VAT collection procedures and provides guidance on the current legal framework affecting these products.
Scope and Applicability
This notice is specifically addressed to all VAT-registered businesses involved in the import, wholesale, or retail sale of mineral waters, aerated waters, soft drinks, and alcoholic drinks. It is essential for traders and distributors operating within these categories to understand the implications of this communication for their compliance obligations and pricing strategies.
Details of the VAT Adjustment Delay
The primary focus of this notice concerns the scheduled implementation of a new VAT collection mechanism at the wholesale level for the specified goods. Originally, this measure was set to commence on 1 April 2014, aiming to streamline VAT collection and improve revenue tracking. However, the Mauritius Revenue Authority has announced that this implementation has been deferred, meaning that the new VAT collection procedures will not take effect on the initially planned date.
This postponement provides businesses with additional time to prepare for potential changes and ensures that the transition will be managed smoothly once the new measures are introduced.
Current VAT Computation and Legal Framework
Despite the delay in the collection mechanism, the legal and fiscal obligations regarding the computation of VAT on these goods remain unchanged. The taxable value—upon which VAT is calculated—continues to be based on the existing rules as stipulated by the prevailing legislation. This means that businesses must continue to apply the current VAT rates and calculation methods until further notice from the authorities.
The legal basis for these regulations is rooted in the VAT Act and related fiscal legislation, which govern the application and collection of VAT across various sectors in Mauritius.
Implications for Businesses and Consumers
For businesses, this notice underscores the importance of maintaining compliance with existing VAT rules during this transitional period. Companies should ensure accurate invoicing, proper record-keeping, and adherence to current tax rates to avoid penalties or audits.
Consumers and end-users should note that, until further notice, the prices of mineral waters, aerated waters, soft drinks, and alcoholic drinks will reflect the current VAT rates and collection procedures. Any potential changes to pricing or tax application will be communicated at a later stage by the MRA.
This temporary measure aims to prevent disruptions in the supply chain and ensure that the tax collection process remains transparent and efficient.
Further Information and Contact Details
For additional guidance or specific inquiries regarding VAT on these goods, VAT-registered persons can contact the Mauritius Revenue Authority through the following channels:
- Telephone: 207 6000
- Fax: 211 8099
- Email: [email protected]
It is advisable for businesses to stay updated on future announcements from the MRA, especially concerning the resumption of the original VAT collection schedule or any modifications to the legal framework.
Conclusion
This official notice highlights the current status of VAT regulation adjustments affecting mineral waters, aerated waters, soft drinks, and alcoholic beverages in Mauritius. While the planned implementation of VAT collection at wholesale level has been deferred, the existing legal and fiscal obligations remain in effect. Businesses are encouraged to monitor official communications from the Mauritius Revenue Authority and ensure ongoing compliance with the prevailing VAT rules during this period of transition.