Official Notice on Corporate Income Tax Filing Deadlines and Penalties
Introduction and Context
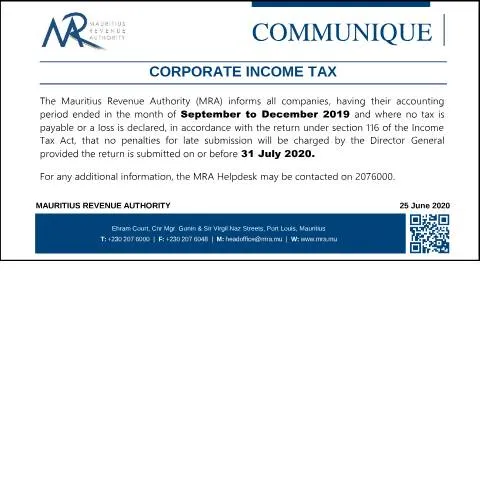
The Mauritius Revenue Authority (MRA) has issued an official notice dated 25 June 2020 concerning the submission of corporate income tax returns for companies with accounting periods ending between September and December 2019. This communication aims to clarify the obligations of affected companies regarding their tax filings, the applicable deadlines, and the conditions under which penalties may be waived.
Scope and Applicability
This notice primarily targets companies operating within Mauritius whose financial year concluded in the last quarter of 2019. Specifically, it applies to entities that have declared either no taxable income or a loss in their tax return filed under section 116 of the Income Tax Act. The instructions are relevant for companies that have not yet submitted their tax return for the relevant period or are in the process of doing so.
Key Provisions and Guidance
Extended Deadline for Submission
The MRA has announced that companies meeting the above criteria will not be subject to penalties for late submission if their tax return is filed on or before 31 July 2020. This extension is granted to facilitate compliance amidst ongoing challenges faced by businesses, particularly considering the context of the COVID-19 pandemic.
Implications for Companies Declaring No Tax Liability or Loss
Companies that declare no tax payable or report a loss in their return are encouraged to ensure their filings are submitted within the specified deadline. The MRA emphasizes that no penalties will be levied for late submissions under these circumstances, provided the return is filed by the deadline. This measure aims to support businesses in maintaining good standing with tax authorities without facing unnecessary financial penalties.
Procedures for Filing and Contact Information
Tax returns must be submitted electronically through the official MRA portal, which is part of the government’s initiative to promote digital services. The MRA’s e-filing system is accessible via the government portal, and companies are advised to utilize their login credentials, which are linked to their corporate tax accounts.
For companies requiring assistance or additional information, the MRA Helpdesk is available at the contact number +230 207 6000. Support services include guidance on the e-filing process, clarification of tax obligations, and other related inquiries.
Legal and Administrative References
This notice is issued in accordance with the provisions of the Income Tax Act and the administrative regulations governing corporate tax filings in Mauritius. The deadline extension and penalty waiver are part of the MRA’s ongoing efforts to facilitate compliance and support the business community during challenging times.
All affected companies are advised to keep abreast of further updates issued by the MRA through official channels, including the agency’s website and direct communications.
Conclusion
The Mauritius Revenue Authority’s communication underscores the importance of timely tax filings and provides relief measures for companies reporting no taxable income or losses for the 2019 fiscal year. By adhering to the extended deadline of 31 July 2020, businesses can avoid penalties and ensure their compliance obligations are met efficiently through the government’s digital platforms.