Overview of the Annual Income Tax Return Submission for Companies
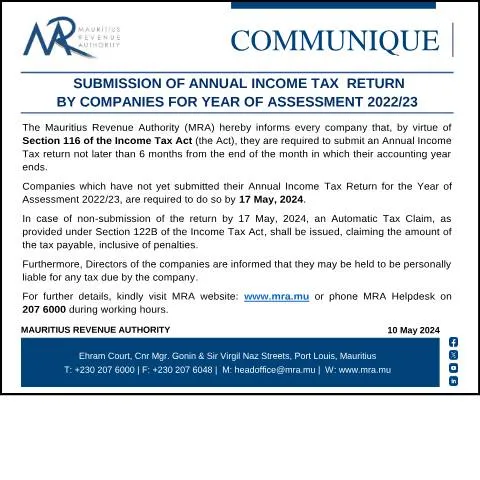
As the deadline looms for the submission of the Annual Income Tax Return for the year of assessment 2022/23, companies in Mauritius must ensure compliance with the statutory requirements set forth by the Mauritius Revenue Authority (MRA). This submission is not merely a procedural formality; it carries substantial implications for the financial health and legal standing of a business. Companies are required to submit their returns no later than May 17, 2024, as stipulated under Section 116 of the Income Tax Act.
Understanding the Implications of Non-Submission
The stakes are high for companies that fail to submit their Annual Income Tax Return by the established deadline. Non-compliance triggers an Automatic Tax Claim under Section 122B of the Income Tax Act, which entails a tax payable that includes penalties. Moreover, the directors of the company may find themselves personally liable for any tax dues, emphasizing the critical nature of timely submissions.
Potential Consequences of Late Filing
- Financial Penalties: Companies could incur additional financial burdens due to penalties imposed for late submissions.
- Legal Accountability: Directors may face personal accountability, affecting their reputation and future business dealings.
- Disruption of Business Operations: Ongoing audits or legal issues can disrupt normal business activities, impacting profitability.
Essential Preparations Before Submission
Preparation is key to a smooth submission process. Companies should ideally begin gathering necessary documents well ahead of the deadline to avoid any last-minute hurdles. Below is a checklist of key documents and information typically required:
Required Documentation
- Financial Statements: This includes balance sheets, profit and loss accounts, and cash flow statements for the relevant accounting period.
- Tax Computation: A detailed computation of tax dues based on the financial statements.
- Supporting Schedules: Any additional schedules that support the tax computation must be attached.
- Director's Report: A report that includes insights into the company's operations and financial performance during the year.
Filling Out the Submission Form
The submission of the Annual Income Tax Return requires meticulous attention to detail when completing the relevant forms. Companies should ensure that all entries are accurate to avoid discrepancies.
Key Sections of the Form
| Section | Description | Details to Include |
|---|---|---|
| Company Information | Basic information about the company | Company name, registration number, and address. |
| Financial Results | Summary of financial performance | Profit before tax, total income, and total expenses. |
| Tax Computation | Calculation of tax liability | Tax rates applied and rationale for any adjustments. |
The Submission Process: Step-by-Step Guide
Once the form is completed, companies should follow a systematic approach to submit their Annual Income Tax Return. The following steps outline the submission process:
Step 1: Review and Finalise Documentation
Prior to submission, companies should conduct a thorough review of all provided documentation. This ensures that no errors or omissions will lead to complications.
Step 2: Online Submission via MRA Portal
The MRA has strongly encouraged the use of its online platform for submissions. Companies must log into the portal using their MauPass single-sign-on, which is linked to their National ID Card. This step not only facilitates a more efficient submission process but also ensures the security of sensitive financial information.
Step 3: Confirmation of Submission
Upon successful submission, an acknowledgment receipt will be generated. Companies must keep this confirmation as a proof of submission, which may be needed for future reference or in case of audits.
Post-Submission Follow-Up: Monitoring Your Tax Return
After the submission, it’s essential for companies to keep track of their tax return status. The MRA provides several mechanisms for follow-up:
Checking Submission Status
- Online Tracking: Companies can log into the MRA online portal to check the status of their tax return.
- Direct Communication: For any concerns or clarifications, companies should reach out to the MRA Helpdesk at +230 207 6000.
Addressing Common Challenges in the Submission Process
Companies may encounter various challenges when preparing and submitting their Annual Income Tax Return. Being aware of these potential issues can facilitate smoother operations.
Identifying Challenges
- Incomplete Documentation: Missing financial statements or tax computations can result in delays.
- Technical Issues: Online portal access problems can hinder timely submissions; it's wise to start early.
- Changes in Tax Legislation: Companies must stay updated on any changes to tax laws that could impact their submissions.
Understanding Your Rights and Obligations
It is crucial for companies to understand their rights and obligations regarding income tax return submissions. Awareness of these aspects not only empowers businesses but also helps mitigate risks associated with non-compliance.
Your Rights as a Taxpayer
- Access to Information: Companies have the right to receive clear information from the MRA regarding tax obligations.
- Right to Appeal: In cases of disputes, companies have the right to appeal MRA decisions.
Your Obligations
- Timely Submission: Companies must adhere to submission deadlines to avoid penalties.
- Accurate Reporting: All reported information must be truthful and precise.
Final Thoughts on the Submission of Income Tax Returns
The successful completion and submission of the Annual Income Tax Return is not only a legal obligation for companies operating in Mauritius but also a crucial component of sound financial management. By diligently preparing documentation, adhering to submission deadlines, and understanding the implications of their tax obligations, companies can navigate the complexities of the tax system more effectively, ensuring compliance and protecting their interests.
As the deadline approaches, companies are encouraged to act promptly, ensuring that all aspects of their tax return are in order. Failure to do so could have significant repercussions that extend beyond mere financial penalties.
Understanding the Tax Obligations for Companies in Mauritius
Filing an Annual Income Tax Return is a crucial obligation for companies operating in Mauritius, particularly for the Year of Assessment 2022/23, which must be submitted by May 10, 2024. Aside from meeting the submission deadline, companies must also ensure compliance with a range of regulations set forth by the Mauritius Revenue Authority (MRA) to avoid penalties and ensure smooth operations. Companies must be aware that their tax obligations extend beyond just the submission of the tax return.
Under the Income Tax Act, companies are required to maintain accurate accounting records that reflect their financial transactions. This includes not only income but also expenses, assets, and liabilities. It is advisable for companies to engage a qualified accountant or tax advisor who understands the nuances of the Mauritian tax framework to ensure that all records are compliant and that the submission is error-free. A key consideration is the requirement to classify revenue streams correctly, particularly for companies involved in international trade or those receiving foreign income, as different tax rules may apply.
Moreover, companies should also be mindful of their obligation to withhold tax on specific payments, such as dividends and royalties. These withholdings must be reported in the annual return, and failing to comply can result in significant fines. Companies may also be subjected to tax audits by the MRA, which can initiate a review of their financial practices and tax submissions. Therefore, maintaining proper documentation and ensuring transparency in financial dealings is paramount.
Filing Procedures for Companies: Step-by-Step Guidance
The process for submitting the Annual Income Tax Return for the Year of Assessment 2022/23 involves several steps that companies must follow meticulously. To facilitate the submission process, all companies are encouraged to use the MRA's e-filing system, which enhances efficiency and reduces the risk of human error compared to traditional paper filing methods.
First, companies must register for an account on the MRA's online portal, which requires a valid National ID number associated with the company’s registered representative. Once registered, companies must gather the necessary documentation, including:
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
- Financial statements audited by a certified accountant.
- Details of income earned during the assessment year.
- Documentation supporting tax deductions claimed, such as receipts and invoices.
- Any tax credits or incentives that the company intends to claim.
After compiling the required documents, companies will access MRA’s online portal using their MauPass credentials. They must select the appropriate form, namely the Income Tax Return Form (IT1), for the relevant year. The electronic form will guide users through each field, ensuring that all required information is filled in accurately. Companies should pay particular attention to sections relating to capital allowances and any tax incentives available in their sector, as these can significantly affect the taxable income.
Once the form is filled out, companies should review it thoroughly to ensure that all information is accurate and complete. Any discrepancies can lead to delays or penalties. Upon final verification, the tax return is submitted electronically. A confirmation receipt will be generated, which companies should retain for their records as proof of submission.
Potential Deductible Expenses for Companies and Strategic Tax Planning
In the context of Mauritian tax law, understanding what qualifies as deductible expenses can play a crucial role in managing the company's tax liability. Deductible expenses reduce the taxable income, thereby decreasing the overall tax liability. Therefore, effective tax planning surrounding deductible expenses is essential for companies aiming to maximize their profitability while remaining compliant with local laws.
Common deductible business expenses include:
- Operating costs such as rent, utilities, and office supplies.
- Salaries and wages paid to employees, along with statutory obligations such as the National Pension Fund (NPF) contributions.
- Depreciation on fixed assets, which allows companies to allocate the cost of tangible assets over their useful lives.
- Professional fees for services rendered by accountants, legal advisors, and consultants.
- Advertising and marketing expenses that directly contribute to generating income.
Additionally, companies should stay informed about any changes in tax regulations that may affect the deductibility of certain expenses. Strategic tax planning should also involve an assessment of the timing of expenses. For instance, if a company anticipates a higher income in the following year, it may be advantageous to defer certain expenses until the next financial year, potentially lowering the current year's tax liability.
Another vital aspect of strategic tax planning is engaging in long-term investments that may qualify for special tax incentives, particularly in sectors targeted for economic growth by the government. Companies can explore various tax incentive schemes available, such as those under the Economic Development Board (EDB), which aims to attract investment into key sectors.
In summary, thorough knowledge of deductible expenses, along with proactive tax planning, can significantly enhance a company’s financial health while ensuring adherence to Mauritian tax obligations.