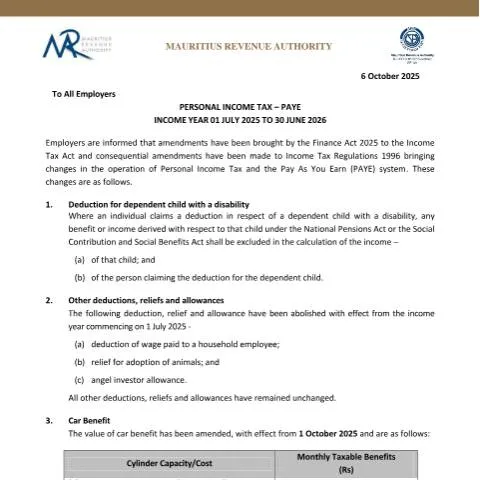
Overview of the Circular to Employers on Payroll Taxes in Mauritius
The Mauritius Revenue Authority (MRA) has issued an official circular aimed at all employers concerning recent amendments to the Personal Income Tax and Pay As You Earn (PAYE) systems, applicable for the income year starting on 1 July 2025 and ending on 30 June 2026. This notice provides essential updates on tax regulations, deductions, benefits, and rates that employers must incorporate into their payroll processes to ensure compliance with the latest legal framework introduced by the Finance Act 2025.
Context and Scope of the Circular
This circular serves as an official guide for employers operating within Mauritius, highlighting key legislative changes affecting payroll taxation. It consolidates amendments made to the Income Tax Act and related regulations, emphasizing the importance of accurate withholding and reporting of taxes under the new provisions. The circular also underscores the Mauritius Revenue Authority’s commitment to enhancing digital compliance through the use of online portals and e-services, aligning with the government’s broader digital transformation objectives.
Key Changes and Their Implications
Adjustments in Deduction for Dependent Children with Disabilities
Employers should note that, starting from this income year, any benefits or income derived by a dependent child with a disability under the National Pensions Act or the Social Contribution and Social Benefits Act are to be excluded when calculating the income of the child and the individual claiming the deduction. This change aims to support families with disabled dependents and streamline tax relief processes.
Elimination of Certain Deductions, Reliefs, and Allowances
Effective from 1 July 2025, the following deductions and reliefs have been abolished:
- Wage paid to household employees
- Relief for the adoption of animals
- Angel investor allowance
Employers should review their payroll systems to ensure these deductions are no longer applied and adjust their tax calculations accordingly.
Revised Car Benefit Valuations
The circular specifies updated monthly taxable benefits for company cars, effective from 1 October 2025, based on engine capacity and vehicle value:
| Type of Car | Cost/Capacity | Monthly Taxable Benefit (Rs) |
|---|---|---|
| Car costing up to Rs 3 million | up to 1,600cc | 12,000 |
| 1,601 to 2,000cc | 13,500 | |
| Above 2,000cc | 15,000 | |
| Electric Car | 13,500 | |
| Car costing more than Rs 3 million | up to Rs 5 million | 25,000 |
| up to Rs 8 million | 35,000 | |
| above Rs 8 million | 50,000 | |
Updated Income Tax Rates and Brackets
The circular outlines the new progressive tax rates applicable to individual taxpayers, effective from 1 July 2025:
| Chargeable Income (Rs) | Tax Rate |
|---|---|
| First 500,000 | 0% |
| Next 500,000 | 10% |
| Remainder | 20% |
Employers must apply these rates appropriately in their monthly PAYE calculations, considering the cumulative chargeable income thresholds outlined in the circular.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Introduction of the Fair Share Contribution
For individuals with income exceeding 12 million rupees annually, a supplementary contribution called the Fair Share Contribution (FSC) is introduced. This levy is calculated at 15% on the income exceeding the threshold, applicable for the income year starting 1 July 2025 and for the subsequent two years. Employers should incorporate this contribution into their payroll withholding for eligible employees, based on the monthly FSC income thresholds specified in the circular.
Practical Guidance for Employers
Employers are encouraged to review their payroll systems to ensure compliance with these new regulations. This includes updating payroll software to reflect the revised car benefit values, tax rates, and deductions, as well as adjusting withholding procedures for employees with high income levels subject to the FSC. Additionally, the circular emphasizes the importance of digital compliance, urging employers to utilize the government’s online portals such as the govmu.org platform for filing and reporting purposes.
References and Further Information
This circular from the Mauritius Revenue Authority is part of the government’s ongoing efforts to modernize tax administration and ensure taxpayers and employers are well-informed of legislative changes. For detailed guidance, employers should consult the official documentation available on the www.mra.mu website or contact the Operational Services Department directly at +230 207 6000 or via email at [email protected].