Understanding the Country by Country Reporting Requirement in Sri Lanka
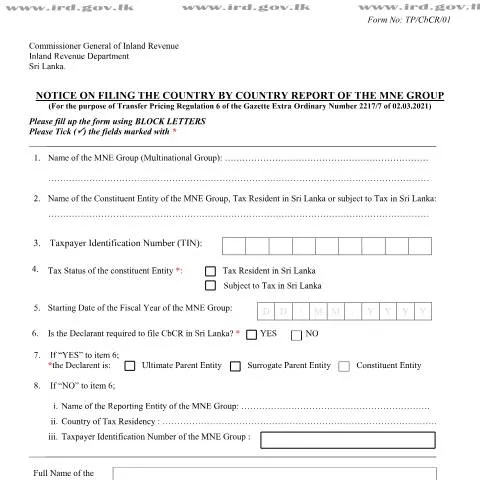
In today's global economy, multinational enterprises (MNEs) face the challenge of ensuring compliance with varied tax regulations across jurisdictions. One such obligation is the Country by Country Reporting (CbCR) requirement, vital for promoting transparency in the taxation of multinational activities. This guide delves into the intricacies of the Notice on Filing of Country by Country Report (CbCR), specifically referenced as TP_CbCR_001, and its relevance to MNEs operating in Sri Lanka.
Decoding the CbCR Notice
The TP_CbCR_001 document serves as a formal notification to MNEs regarding their obligation to file a CbCR in compliance with Transfer Pricing Regulation 6, as stipulated in the Gazette Extra Ordinary Number 2217/7 dated 2nd March 2021. This regulation aims to ensure that MNEs provide a comprehensive breakdown of their financial activities across different territories to local tax authorities.
Key Components of the CbCR Notice
- MNE Group Name: The document starts with the identification of the MNE Group, which is crucial for linking the report to the correct entity.
- Constituent Entity Name: This portion requires the name of the entity that is tax resident in Sri Lanka, ensuring the local entity's compliance.
- Taxpayer Identification Number (TIN): The TIN serves as a unique identifier for the constituent entity, allowing for streamlined processing by the Inland Revenue Department.
- Tax Status: It's vital to indicate whether the constituent entity is tax resident or subject to tax in Sri Lanka.
Furthermore, the document prompts the declarant to confirm if they are required to file a CbCR, providing options such as 'Ultimate Parent Entity', 'Surrogate Parent Entity', or 'Constituent Entity'. This categorization is critical as it determines the reporting obligations and the entity that will be liable for submission of the report.
Step-by-Step Guide to the CbCR Process
Understanding the process of submitting the CbCR is essential for compliance and mitigation of penalties. The following steps provide a structured approach for MNEs:
- Identify Reporting Obligation: Confirm whether the entity is required to file the CbCR in Sri Lanka.
- Gather Necessary Information: Compile relevant data including financial statements, details of the MNE Group, and information about constituent entities.
- Complete the CbCR Notice: Use block letters to fill out the TP_CbCR_001 form, ensuring accuracy and clarity.
- Submission: Submit the completed report to the Inland Revenue Department by the stipulated deadline.
Articulating the Interactions with Other Documentation
The CbCR notice does not exist in isolation. It interacts with various other documents necessary for tax compliance:
- Transfer Pricing Documentation: This includes contemporaneous documentation justifying the pricing strategies employed by the MNE.
- Financial Statements: Audited financial statements are often required to supplement the information provided in the CbCR.
- Local File Requirements: Depending on the jurisdiction, local files may be necessary for providing detailed insights into specific transactions.
Each document complements the CbCR and presents a holistic view of the MNE's business operations within Sri Lanka and abroad.
Essential Terminology for Clarity
To navigate the CbCR effectively, it is essential to grasp the specific terminology associated with the document:
| Term | Definition |
|---|---|
| Multinational Enterprise (MNE) | An enterprise that operates in two or more countries. |
| Transfer Pricing | The rules and methods for pricing transactions between enterprises under common ownership or control. |
| Constituent Entity | A legal entity that is part of the MNE Group and is subject to taxation. |
| Ultimate Parent Entity | The top-tier entity within the MNE Group that consolidates financial statements. |
Common Misinterpretations and Pitfalls
Entities may encounter challenges while navigating the CbCR requirement. Some common misinterpretations include:
- Assuming all MNEs are exempt: Not all MNEs qualify for exemptions. It's crucial to verify specific thresholds and conditions.
- Incorrectly identifying the Reporting Entity: The choice between declaring as an Ultimate Parent Entity or a Constituent Entity should be based on clear criteria outlined in the regulation.
- Neglecting local compliance: Even if a CbCR is filed in another jurisdiction, local filing obligations must still be met if the entity is tax resident in Sri Lanka.
Scope and Limitations of the CbCR Notice
The CbCR Notice outlines specific requirements aimed at creating transparency in tax reporting. However, it does have its limitations:
- Exemptions: Certain entities may be exempt based on their size, revenue, or nature of operations, which should be thoroughly reviewed.
- Confidentiality Concerns: While the report promotes transparency, it may raise concerns regarding the confidentiality of sensitive business information.
- Regulatory Changes: As international tax regulations evolve, MNEs must remain vigilant to ensure continued compliance with any amendments to the CbCR requirements.
Practical Tips for Effective Compliance
To aid MNEs in fulfilling their obligations under the CbCR requirements, consider the following practical strategies:
- Establish a Dedicated Compliance Team: Appoint a team responsible for understanding and managing compliance obligations related to international taxation.
- Implement Efficient Data Management Systems: Utilize technological solutions that facilitate the gathering, analysis, and reporting of financial data across jurisdictions.
- Ongoing Training and Awareness: Regularly train staff on the evolving tax landscape and ensure the team is well-informed about the requirements of the CbCR process.
By adopting these practices, MNEs can mitigate risks and enhance their compliance framework while navigating the complexities of international tax regulations.
Conclusion: Navigating the Future of CbCR in Sri Lanka
The Notice on Filing of Country by Country Report (CbCR) is a significant component of the regulatory framework governing multinational enterprises in Sri Lanka. By understanding the document's requirements and its interactions with other compliance obligations, MNEs can ensure adherence to the regulatory landscape while promoting transparency and accountability in their operations. As tax regulations evolve, continual adaptation and awareness are imperative to maintain compliance and avoid potential penalties.
Understanding the Country by Country Reporting (CbCR) Compliance Framework
The Country by Country Reporting (CbCR) framework introduced in Sri Lanka is guided by the principles outlined in the Base Erosion and Profit Shifting (BEPS) Action Plan, which seeks to improve tax transparency for multinational enterprises (MNEs). This requirement applies to MNEs that meet specific thresholds, typically determined by consolidated revenue criteria. The primary goal is to allow tax authorities to assess potential risks related to aggressive tax planning and ensure compliance with local tax laws.
MNEs operating in Sri Lanka are expected to submit the CbCR to the Department of Inland Revenue (DIR) through the prescribed Notice on filing of Country by Country Report, commonly referred to as TP_CbCR_001_E. This electronic form can be submitted via the DIR’s digital platform or as a hard copy at the relevant regional office. Organizations must keep abreast of the filing deadlines, as any failures in compliance could result in penalties or increased scrutiny from tax authorities.
In the context of Sri Lankan regulations, it is crucial for companies to monitor the changes in the notification process, as the DIR periodically updates guidelines to align with international standards. Additionally, MNEs are encouraged to maintain robust documentation that supports the data provided in the CbCR to defend against any potential audits. This emphasizes the importance of thorough record-keeping and internal review processes within the organization.
Best Practices for Preparing and Submitting the CbCR
Submitting the Country by Country Report (CbCR) requires meticulous preparation and adherence to various best practices to ensure successful compliance with Sri Lankan regulations. First, it is advisable to conduct a thorough analysis of the MNE's organizational structure. This includes identifying all jurisdictions in which the group operates, as this information forms the basis of the CbCR. Understanding the interconnectedness of the group’s subsidiaries and their revenue contributions is vital for accurate reporting.
Secondly, organizations should invest time in gathering and consolidating financial data across different territories. As the CbCR requires reporting on revenue, profit before tax, and taxes paid, it is essential to ensure that this data is not only accurate but also aligned with the accounting standards used in Sri Lanka. Engaging with tax professionals who are well-versed in local tax laws can facilitate this process and mitigate risks associated with misreporting.
Another critical aspect is the timely submission of the TP_CbCR_001_E form. MNEs must be acutely aware of the deadlines set by the DIR, which may differ based on the financial year and specific regulatory updates. Establishing a calendar for compliance activities can help ensure that submissions are made on time and allow for adequate review prior to submission. Additionally, organizations should consider establishing a compliance team that is dedicated to handling CbCR submissions and monitoring developments in tax regulations.
Keeping abreast of international developments related to BEPS and CbCR is also necessary for companies. Participating in workshops and seminars focusing on tax compliance can provide valuable insights into evolving regulations and best practices. This proactive approach not only enhances compliance but also prepares the organization for potential future adjustments to the CbCR framework in Sri Lanka.
Potential Challenges and Ways to Mitigate Them
As MNEs prepare to submit the Country by Country Report (CbCR) in Sri Lanka, they may encounter several challenges that could hinder compliance. Understanding these challenges and proactively addressing them can help organizations navigate the complexities of the CbCR requirement more smoothly.
One of the significant challenges is the availability and accuracy of data across various jurisdictions. Different subsidiaries may use diverse accounting practices and fiscal year-end dates, making it difficult to consolidate data for the CbCR. To mitigate this, MNEs should implement standardized reporting practices across their global operations. This involves aligning financial systems and procedures to ensure consistency in data collection and reporting.
Another challenge arises from potential discrepancies in tax laws and transfer pricing regulations among jurisdictions. Different countries may have varying interpretations of the BEPS guidelines, leading to complications in reporting. To address this, MNEs should engage with local tax advisors in each jurisdiction to ensure that their CbCR is compliant with both local and international standards. Furthermore, holding regular meetings with regional tax teams can help promote clarity and alignment within the organization regarding CbCR compliance.
Lastly, MNEs may face time constraints when preparing the CbCR, especially if their financial year-end does not align with the reporting timeline set by the DIR. To counter this, companies should start preparing their CbCR data well ahead of the deadline, enabling them to allocate adequate resources for thorough reviews and necessary adjustments. Utilizing project management methodologies can help streamline the data collection and reporting process, allowing for better time management and oversight.