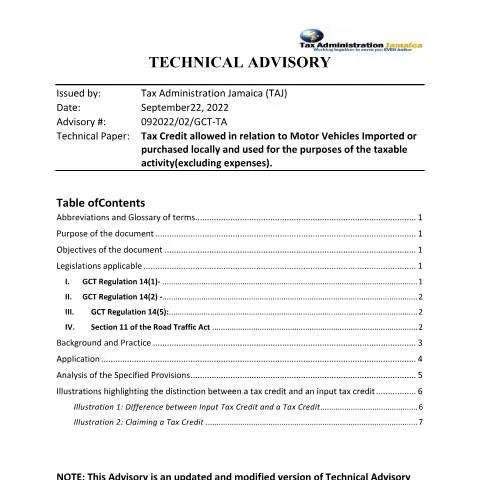
Understanding the Technical Advisory on Tax Credit for Motor Vehicles in Jamaica
The Jamaican Tax Administration Jamaica (TAJ) issued a comprehensive Technical Advisory on September 22, 2022, to clarify the application of tax credits related to motor vehicles used in taxable activities. This advisory, titled Tax Credit allowed in relation to Motor Vehicles, provides essential guidance for registered taxpayers, especially those involved in importing or purchasing motor vehicles for business purposes. This article aims to explain the key points of this advisory, its scope, and how it impacts taxpayers in Jamaica.
Purpose and Scope of the Advisory
The primary purpose of this Technical Advisory is to clarify how registered taxpayers can claim a tax credit on motor vehicles that are used to facilitate or enable their taxable activities. It explicitly excludes motor vehicles acquired as stock-in-trade for resale, which are instead eligible for input tax credits. The advisory applies to motor vehicles used for business purposes, such as transportation, logistics, or other taxable operations, and aims to ensure taxpayers understand the legal framework governing these claims.
Legal Foundations and Relevant Regulations
The advisory references several key legal provisions under the General Consumption Tax (GCT) Act 1991, including:
- GCT Regulation 14(1): Defines the general entitlement of registered taxpayers to claim input tax credits during a taxable period.
- GCT Regulation 14(2): Specifies the scope of input tax that can be claimed, including tax on taxable supplies and importation of goods used in taxable activities.
- GCT Regulation 14(5): Details the specific percentage-based tax credits applicable to motor vehicles, depending on their classification and usage.
- Section 11 of the Road Traffic Act: Provides legal context for motor vehicle registration and usage, impacting how tax credits are applied.
Criteria for Claiming the Tax Credit
Taxpayers can claim a tax credit on motor vehicles used for their taxable activities, but several conditions apply:
- The vehicle must be purchased or imported and used solely for facilitating taxable activities.
- The vehicle should not be acquired as stock-in-trade for resale, as such purchases qualify for input tax credits instead.
- The total cost of the vehicle for tax credit purposes includes the CIF (Cost, Insurance, Freight) value, Customs Duty, Additional Stamp Duty, Special Consumption Tax, and other applicable fees and levies, with a maximum value of US$35,000.
- The applicable tax credit percentages depend on the specific regulation, with examples including 6.5% or 13% of the vehicle's cost, inclusive of tax.
How to Calculate and Claim the Tax Credit
Claiming a tax credit involves calculating the eligible amount based on the vehicle's total cost and the applicable percentage. For example, if a vehicle's total cost (including all applicable taxes and duties) is within the maximum limit, the taxpayer can claim a percentage of that amount as a tax credit in their GCT return.
The advisory provides illustrative examples to differentiate between an input tax credit and a tax credit:
- Input Tax Credit: Typically claimed on goods acquired for resale or input purposes, allowing the taxpayer to offset the GCT paid on such inputs against their GCT liabilities.
- Tax Credit: A specific percentage of the vehicle's cost, applicable when the vehicle is used for taxable activities, as outlined in Regulation 14(5).
Points of Attention and Practical Advice
Taxpayers should be cautious to ensure:
- Proper documentation is maintained, including invoices, import documentation, and proof of vehicle usage for taxable activities.
- The vehicle's purchase or import cost is accurately calculated, including all relevant taxes and duties, up to the maximum limit.
- The vehicle is used exclusively for taxable activities to qualify for the tax credit, and any non-taxable use could disqualify the claim.
- Claims are made within the applicable tax period, aligning with the GCT filing deadlines.
Conclusion
This Technical Advisory provides critical guidance for Jamaican businesses and registered taxpayers seeking to maximize their tax credits on motor vehicles used in their taxable activities. By understanding the applicable regulations and maintaining proper documentation, taxpayers can ensure compliance and optimize their tax benefits related to vehicle purchases and imports.