Understanding the Payroll Taxes and Contribution Rates for Self-Employed Pensioners in Jamaica
This official document provides essential guidance for self-employed pensioners in Jamaica regarding the applicable payroll taxes and contribution rates. It is designed to assist pensioners who operate their own businesses and need to comply with the country's tax and social security contribution requirements. The document outlines the rates, calculation methods, and important considerations to ensure accurate reporting and payment of contributions and taxes.
Scope and Applicability
This reference is specifically tailored for self-employed pensioners who earn income through their business activities and receive pension income from the National Insurance Scheme (NIS). It applies to individuals aged 65 and above who are managing their own enterprises and are subject to Jamaica’s payroll contribution obligations under the Revenue Administration Act and related social security laws.
Payroll Contribution Rates for Self-Employed Pensioners
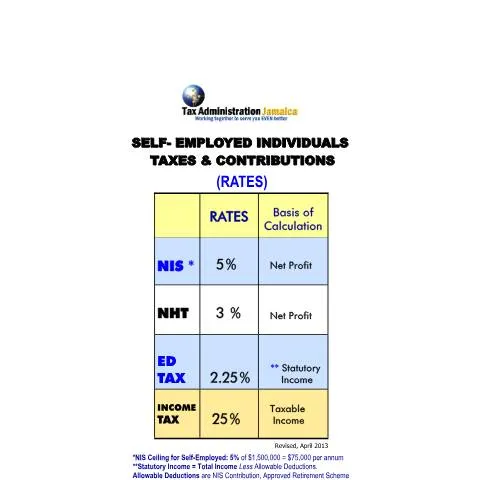
The document specifies the contribution rates based on the statutory income of the pensioner’s business activities and other income sources. The rates are as follows:
- National Insurance Scheme (NIS): 5% of the net profit, with a ceiling of 5% of $1,500,000, equating to a maximum annual contribution of $75,000.
- National Housing Trust (NHT): 3% of the net profit.
- Education Tax (ED TAX): 2.25% of the net profit.
- Income Tax: Calculated at a rate of 25% on the taxable income after deductions.
These rates are applied to the statutory income, which is derived from the net profit of the business, adjusted for allowable deductions and exemptions.
Calculating Taxable Income and Contributions
The process involves several steps:
- Determine Gross Receipts: Total income generated from business operations.
- Deduct Business Expenses: Operational costs such as rent, wages, and cost of sales to arrive at the gross profit.
- Calculate Net Profit: Gross profit minus administrative expenses.
- Add Other Income Sources: Include NIS pension income and rental income to obtain total income.
- Apply Allowable Deductions: Capital allowances, pension and age reliefs, and other permitted deductions are subtracted to determine statutory income.
- Determine Taxable Income: Subtract the income tax threshold from the statutory income.
The resulting taxable income is then used to calculate the income tax payable at the applicable rate of 25%. The contribution amounts for NIS, NHT, and EDU TAX are calculated based on the net profit or statutory income, with specific ceilings and allowances applied.
Important Points and Advice for Self-Employed Pensioners
- Ceiling on NIS Contributions: The maximum contribution is capped at 5% of $1,500,000, i.e., $75,000 annually.
- Allowable Deductions: Ensure all eligible deductions such as capital allowances, pension reliefs, and age reliefs are accurately claimed to reduce taxable income.
- Documentation and Record-Keeping: Maintain detailed records of all business expenses, receipts, and income sources to support your calculations during audits or reviews.
- Filing and Payment Deadlines: Contributions and income taxes are due annually, aligned with the fiscal year, with specific deadlines set by the Tax Administration Jamaica (TAJ).
- Use of Official Forms: Complete the relevant forms such as the self-employed income tax return and contribution schedules, following the instructions provided by TAJ.
Additional Resources and Support
For further assistance, self-employed pensioners can contact the Tax Administration Jamaica (TAJ) through their helpline at 1-888-TAX-HELP (829-4357) or visit their official website at www.jamaicatax.gov.jm. The TAJ also offers online services and guidance to facilitate compliance with tax obligations.
Understanding and correctly applying these contribution rates and calculations are vital for self-employed pensioners to remain compliant with Jamaican tax laws and social security contributions. Proper planning and record-keeping will ensure smooth processing during tax assessments and help avoid penalties or interest charges.