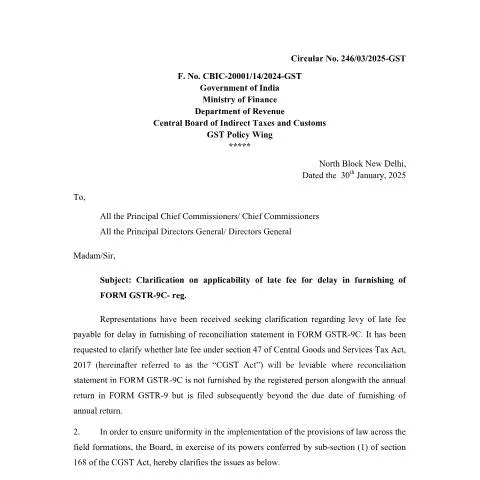
Official Circular No. 246/03/2025-GST: Clarification on Late Fee for Delay in Filing GSTR-9C
The Government of India, through the Central Board of Indirect Taxes and Customs (CBIC), has issued Circular No. 246/03/2025-GST on January 30, 2025, to provide essential clarifications regarding the applicability of late fees for delays in submitting the reconciliation statement in FORM GSTR-9C. This circular aims to ensure uniformity in the implementation of GST compliance requirements across all field formations and to clarify the circumstances under which late fees are applicable for delayed filings.
Context and Background of the Circular
The circular arises from multiple representations received by the CBIC seeking clarity on whether late fees under section 47 of the Central Goods and Services Tax (CGST) Act, 2017, are applicable when a registered taxpayer files the reconciliation statement in FORM GSTR-9C after the due date along with the annual return in FORM GSTR-9. Prior to August 1, 2021, the law mandated that the reconciliation statement in FORM GSTR-9C be filed only by those taxpayers required to get their accounts audited under section 35(5) of the CGST Act, typically those with an aggregate turnover exceeding two crore rupees.
However, post the amendment on August 1, 2021, the threshold for filing the reconciliation statement was increased to an aggregate turnover exceeding five crore rupees, and the filing deadline was set as December 31 following the end of the financial year. The circular clarifies the legal interpretation of these provisions, especially concerning late fee liability in cases of delayed filing.
Scope of the Clarification
This circular specifically addresses the following key issues:
- The legal obligation to file both FORM GSTR-9 and FORM GSTR-9C for applicable taxpayers.
- The circumstances under which late fee is applicable for delays in submitting these forms.
- The calculation of late fees when both forms are required but filed late.
Mandatory Filing of GSTR-9 and GSTR-9C
According to the provisions clarified in this circular, a registered person required to furnish an annual return in FORM GSTR-9 must also submit a reconciliation statement in FORM GSTR-9C if their aggregate turnover during the financial year exceeds the specified threshold. The reconciliation statement is intended to reconcile the declared supplies in FORM GSTR-9 with the audited financial statements, ensuring transparency and compliance.
It is important to note that the requirement to file FORM GSTR-9C is only triggered if the taxpayer's turnover exceeds the prescribed limit, and the form must be filed along with the annual return.
Implication for Late Filing and Late Fee
The circular emphasizes that late fee under section 47(2) of the CGST Act is applicable only when the complete annual return—comprising both FORM GSTR-9 and FORM GSTR-9C where applicable—is not filed by the due date. The late fee is calculated for the period from the due date of the annual return until the date when the complete return is furnished.
Specifically, if a taxpayer files only FORM GSTR-9 without the required FORM GSTR-9C (when applicable), the filing cannot be considered complete, and late fee may be levied for the delay in submitting the entire set of required documents. The circular clarifies that late fees are not separately charged for the delay in filing each form but are computed based on the period of non-compliance with the complete filing obligation.
Conclusion and Practical Implications
This circular provides crucial guidance for registered taxpayers and GST practitioners on the legal position regarding late fees for delayed filings of annual returns and reconciliation statements. It underscores the importance of timely and complete submission of both FORM GSTR-9 and FORM GSTR-9C where applicable to avoid penalties.
Taxpayers are advised to review their filing obligations carefully, especially in the context of their turnover thresholds, to ensure compliance with the GST law and avoid late fee liabilities. The circular aims to standardize the approach across all GST field formations, promoting clarity and consistency in enforcement.