Understanding the VAT 60A Application Form for Foreign Traders in Ireland
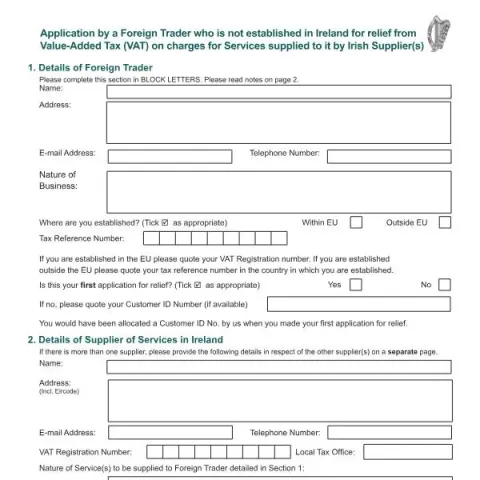
The VAT 60A form is an official document issued by the Office of the Revenue Commissioners in Ireland. It is designed for foreign traders who are not established within Ireland but wish to obtain relief from Value-Added Tax (VAT) on charges for services supplied to them by Irish suppliers. This article provides a comprehensive overview of the form's purpose, eligibility criteria, and the step-by-step procedure for completing and submitting it.
Purpose and Scope of the VAT 60A Form
The primary objective of the VAT 60A application is to facilitate relief from Irish VAT for foreign traders who do not have a fixed establishment in Ireland but receive services from Irish suppliers. This relief is particularly relevant for international businesses engaging in cross-border transactions, ensuring they are not unfairly taxed on services used solely for their business activities outside Ireland.
The form is applicable to traders established outside Ireland, whether within or outside the European Union (EU). It covers various service types supplied by Irish suppliers, including consultancy, legal, financial, and other professional services. The relief granted through this process aims to prevent double taxation and streamline international trade operations.
Eligibility Conditions for Applying
- The applicant must be a foreign trader not established in Ireland, with no fixed establishment or permanent place of business in the country.
- The services for which relief is sought must be supplied by Irish suppliers and solely used for the applicant’s business activities outside Ireland.
- The applicant should not be registered for VAT in Ireland nor be required to register, which can be confirmed through the relevant tax authorities.
- The applicant must provide supporting documentation, such as a certificate of taxable status from their country’s tax authority, to verify their non-establishment status.
- If the applicant has previously applied for relief, they should include their Customer ID number, if available.
Step-by-Step Guide to Completing the Form
1. Filling in the Foreign Trader Details
Begin by providing the trader’s information in BLOCK LETTERS, including:
- Name of the trader or company
- Address, including the Eircode if applicable
- Email and telephone contact details
- Nature of the business activity
Next, specify the trader’s establishment status:
- Tick the box indicating whether the trader is established within or outside the EU.
- Provide the relevant tax reference number or VAT registration number, depending on the establishment location.
- Indicate if this is the first application or a subsequent one by including the Customer ID number, if available.
2. Providing Irish Supplier Details
For each Irish supplier involved, complete the following:
- Name and address, including the Eircode
- Email and telephone contact details
- VAT registration number of the supplier
- Local tax office handling the supplier’s registration
Additionally, specify the nature of the services provided, whether they will be supplied on a continuous basis, and whether the Irish supplier holds or will hold stocks of goods in Ireland on behalf of the applicant.
3. Declaration and Signature
Before submitting, the applicant must read and sign the declaration confirming that:
- No goods or services are supplied in Ireland for the applicant’s business purpose.
- The applicant is not established or registered for VAT in Ireland.
- The services will be used solely for their business outside Ireland.
- All information provided is accurate and complete.
The declaration must be signed by an authorized person, such as a company director or secretary, and dated accordingly.
Supporting Documentation and Submission
Applicants are required to attach specific supporting documents, including:
- A certificate of taxable status from their national tax authority if established within the EU.
- A certificate from the relevant authority if established outside the EU, containing details such as the business name, address, registration number, and nature of economic activity.
- A certified copy of the lease if the business involves leasing premises.
The completed form, along with supporting documents, should be sent to:
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Office of the Revenue Commissioners, Collector-General’s Division, Unregistered VAT Repayment Section, Sarsfield House, Francis Street, Limerick, V94 R972.
Important Considerations and Deadlines
Applicants should ensure all sections are fully completed and signed before submission. Incomplete forms or missing documentation may delay processing or result in rejection. The form should be submitted promptly to meet any applicable deadlines, especially if the relief is to be applied within a specific tax period.
It is advisable to retain copies of all submitted documents and correspondence for future reference. The Revenue Commissioners may request additional information or clarification during the review process.
Final Notes
Applying for relief using the VAT 60A form is a crucial step for foreign traders seeking to avoid unnecessary VAT costs on Irish services. By carefully completing the form and providing accurate supporting documentation, applicants can benefit from streamlined VAT treatment, facilitating smoother international trade operations.