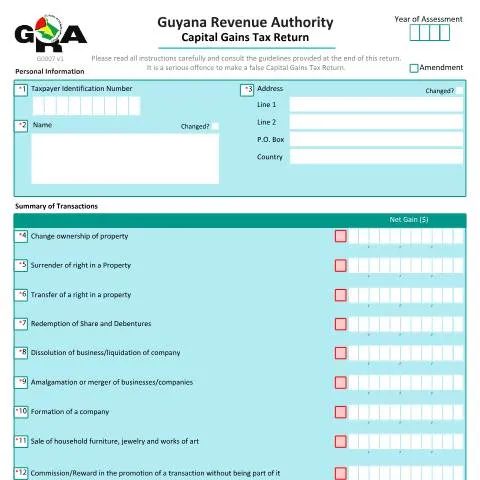
Understanding the Capital Gains Tax Return Form G0007 CGT v1 in Guyana
The G0007 CGT v1 form is an official administrative document issued by the Guyana Revenue Authority (GRA) designed for reporting capital gains transactions. This form is essential for individuals and entities involved in transactions that may generate capital gains, such as property transfers, share redemptions, or business mergers. Proper completion and submission of this form are crucial for compliance with Guyanese tax legislation and to ensure accurate calculation and payment of capital gains tax.
Purpose and Scope of the Form
The primary purpose of the G0007 CGT v1 form is to provide the GRA with a comprehensive summary of taxable capital gains realized during the assessment year. It captures details of various types of transactions that could lead to capital gains, including:
- Ownership changes of property
- Surrender or transfer of property rights
- Redemption of shares and debentures
- Business dissolution or liquidation
- Amalgamation or merger of companies
- Formation of a new company
- Sale of household furniture, jewelry, and works of art
- Commission or reward for facilitating transactions
The form also calculates the net capital gain, applicable tax rate, and the total tax payable, thus providing a clear overview of the taxpayer’s obligations for the assessment period.
Who Must Complete the Form?
This form must be completed by any individual or legal entity that has engaged in taxable capital gain transactions within the assessment year. This includes:
- Property owners involved in sale or transfer
- Shareholders redeeming shares or debentures
- Companies undergoing liquidation, merger, or formation
- Individuals selling personal assets such as jewelry or artwork
- Persons earning commissions or rewards related to transaction facilitation
Taxpayers are responsible for ensuring that all relevant transactions are accurately reported, and that the form is submitted timely to avoid penalties.
How to Complete the Form
Completing the G0007 CGT v1 requires careful attention to detail and supporting documentation. The form is divided into several sections:
1. Signature and Declaration
At the top, the authorized signatory must indicate their role (e.g., proprietor, director, manager) and sign the form, certifying that the information provided is true and correct. The date of signing must also be included.
2. Assessment and Taxpayer Details
Provide the year of assessment, Taxpayer Identification Number (TIN), and full name. The address must be complete, including country and postal information.
3. Transaction Details
Specify the nature of each transaction, such as transfer, surrender, or sale, and include relevant details like ownership change, property rights, or business mergers. If any information has changed from previous filings, this should be clearly indicated.
4. Financial Calculations
Fill in the net chargeable capital gain, applicable tax rate (percentage), and total tax payable. It is vital to ensure these calculations are accurate, as they determine the taxpayer’s liability.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
5. Additional Information and Attachments
Any supplementary details or supporting documents, such as sale agreements, transfer deeds, or valuation reports, should be attached to substantiate the reported transactions.
Supporting Documents and Submission
Taxpayers must submit the completed form along with all relevant supporting documents to the GRA’s offices. The submission can typically be made in person at the GRA headquarters or designated tax offices, or via authorized electronic channels if available. It is recommended to keep copies of all submitted documents for future reference.
Common Errors to Avoid
- Omitting transaction details or providing incomplete information
- Incorrect calculation of net gains or taxes due
- Failure to attach necessary supporting documents
- Submitting the form after the deadline, which may lead to penalties
Ensuring accuracy and completeness in the G0007 CGT v1 form helps prevent delays, penalties, and potential audits. Taxpayers are encouraged to consult the official GRA guidelines or seek professional advice if unsure about specific entries or procedures.
Conclusion
The G0007 CGT v1 form is a vital compliance tool for reporting capital gains in Guyana. Proper understanding of its purpose, careful completion, and timely submission are essential for fulfilling tax obligations and maintaining good standing with the Guyana Revenue Authority. For further guidance, taxpayers should refer to the official GRA resources or contact their local tax office.