Understanding the Application for Endorsement for Charity Tax Concessions in Australia
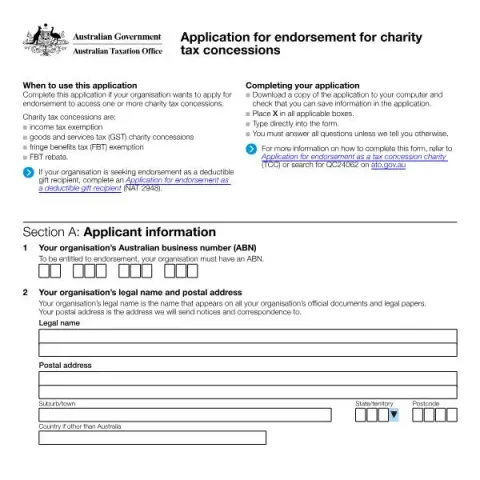
If your organisation is a registered charity or not-for-profit entity seeking to access specific tax benefits, you will need to complete the Application for endorsement for charity tax concessions (form code: NAT 10651). This official form, issued by the Australian Taxation Office (ATO), is essential for organisations aiming to obtain endorsement for various tax concessions, including income tax exemption, goods and services tax (GST) charity concessions, fringe benefits tax (FBT) exemption, and FBT rebate.
When Should Your Organisation Use This Form?
This form is designed for organisations that wish to be endorsed by the ATO to access one or more of the following charity tax concessions:
- Income tax exemption
- GST charity concessions
- FBT exemption
- FBT rebate
If your organisation is also seeking endorsement as a deductible gift recipient (DGR), you will need to complete a different application, specifically the Application for endorsement as a deductible gift recipient (NAT 2948).
Steps to Complete the Application
Before filling out the form, ensure you have downloaded a copy to your computer, allowing you to save your progress. The form is designed to be completed electronically by placing an X in all applicable boxes and typing directly into the fields. It is crucial to answer all questions unless instructed otherwise. For detailed guidance, you can refer to the instructions associated with the form, such as the document titled Application for endorsement as a tax concession charity (TCC) or search for QC24062 on the ATO website.
Key Sections of the Application
Section A: Organisation Details
This section requires basic information about your organisation, including:
- Australian Business Number (ABN): Your organisation must hold an ABN to be eligible for endorsement.
- Legal Name and Postal Address: The official name registered with authorities and the address for correspondence.
Additionally, you will need to specify the extent of your organisation’s activities outside Australia and the percentage of expenses related to offshore purposes. These details help determine eligibility for certain concessions that are limited to domestic activities.
Section B: ACNC Registration
Charities must be registered with the Australian Charities and Not-for-profits Commission (ACNC) before applying for endorsement. You will need to provide the registration date or indicate if your organisation is not registered, which would disqualify you from accessing charity tax concessions.
Section C: Income Tax Exemption
To seek endorsement for income tax exemption, your organisation must meet specific criteria:
- Compliance with governing rules ensuring income and assets are used solely for the organisation’s purposes.
- Answering questions about the date from which the exemption should apply.
If your organisation is new or does not meet these requirements, endorsement for income tax exemption will not be granted.
Section E and F: FBT Endorsements and Rebates
These sections relate to applications for FBT exemption and rebates. Endorsement for FBT exemption is available for registered health promotion charities (HPCs) and public benevolent institutions (PBIs) that are not hospitals. The FBT rebate offers a rebate of 48% of gross FBT payable, capped at $30,000 per employee, but only for endorsed charities that are institutions and have income tax exemption endorsement.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Important Points to Consider
Applying for these endorsements requires careful attention to detail, especially regarding the organisation’s registration status, governing rules, and the scope of activities both within and outside Australia. Make sure to provide accurate dates for when you wish the endorsements to commence, as the start date for FBT rebates must be the same or later than the income tax exemption endorsement date.
It is also essential to review the eligibility criteria for each concession type and ensure your organisation’s structure and activities align with the requirements set by the ATO. Failure to meet these criteria may result in the application being refused or endorsements being denied.
Conclusion
The NAT 10651 form is a vital step for charities and not-for-profits in Australia seeking to benefit from tax concessions. Properly completing the application, with all relevant details and supporting information, will facilitate a smoother endorsement process. For further guidance, consult the official instructions or visit the ATO website to ensure compliance with current requirements and procedures.