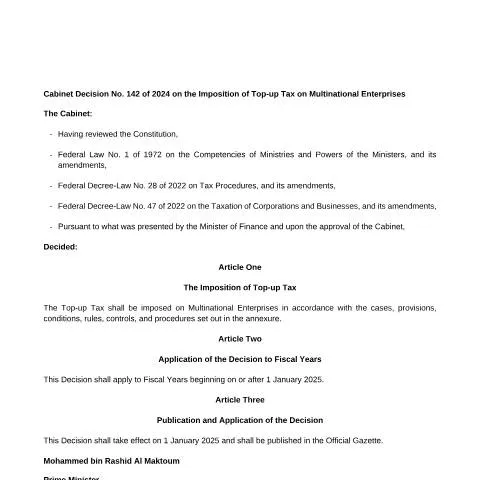
Overview of the Cabinet Decision No (142) of 2024 on the Imposition of Top-up Tax on Multinational Enterprises in the UAE
The United Arab Emirates has introduced a significant legislative measure aimed at aligning its tax framework with international standards for fair taxation of multinational enterprises (MNEs). The Cabinet Decision No (142) of 2024 establishes the legal basis for imposing a top-up tax on qualifying MNEs operating within the UAE. This decision reflects the country's commitment to enhancing transparency, ensuring compliance with global tax initiatives, and fostering a competitive yet equitable fiscal environment.
Scope and Objectives of the Legislation
This decision primarily targets multinational corporations that generate substantial revenues within the UAE and are subject to global minimum tax agreements. Its main objective is to prevent profit shifting and base erosion by ensuring that MNEs pay an appropriate level of tax on their global income, including profits attributable to their activities in the UAE.
By implementing a top-up tax, the legislation seeks to complement existing corporate tax regulations, ensuring that MNEs contribute fairly to the UAE’s economic development and public service funding. This measure aligns with the UAE's broader strategy to enhance its international tax compliance and attract sustainable foreign investment.
Key Provisions and Compliance Requirements
Determination of Taxable Entities
The decision applies to multinational enterprises that meet specific criteria related to their global revenue thresholds and operational presence in the UAE. Entities falling within this scope are required to assess their tax liabilities carefully and ensure adherence to the new obligations.
Calculation and Application of the Top-up Tax
The legislation stipulates that the top-up tax will be calculated based on the difference between the effective tax paid in the jurisdiction of the MNE's global operations and the minimum tax rate stipulated by international agreements or UAE regulations. The tax authorities will oversee the calculation process, requiring entities to submit relevant documentation and disclosures.
Reporting and Documentation
Entities subject to this legislation must maintain detailed records of their global income, tax payments, and related financial data. They are also expected to submit comprehensive reports through designated digital platforms managed by the Federal Tax Authority (FTA). These reports will facilitate transparency and enable the authorities to verify compliance efficiently.
Implications for Multinational Enterprises and Tax Authorities
For multinational enterprises operating in the UAE, this legislation introduces an additional compliance layer. Companies must review their tax planning strategies, ensure accurate reporting, and maintain robust documentation to demonstrate adherence to the new rules. Non-compliance could result in penalties or other administrative measures enforced by the FTA.
Tax authorities will leverage digital tools and data analytics to monitor and enforce compliance, reflecting the UAE’s commitment to a highly digitalized and transparent tax system. The FTA will coordinate with international tax bodies to ensure the effective implementation of the top-up tax regime and uphold the UAE's reputation as a compliant and attractive destination for foreign investment.
Conclusion: A Step Towards International Tax Alignment
The enactment of Cabinet Decision No (142) of 2024 signifies the UAE’s proactive approach to international tax standards and its dedication to fostering a fair and transparent fiscal environment. Multinational enterprises operating within the country should stay informed about their obligations under this new legislation and prepare for enhanced reporting and compliance procedures.
For detailed guidance and official updates, entities are advised to consult directly with the Federal Tax Authority (FTA) and monitor official communications through the UAE’s digital government portals. This legislation underscores the UAE’s ongoing efforts to align with global best practices and maintain its position as a responsible and competitive economic hub.