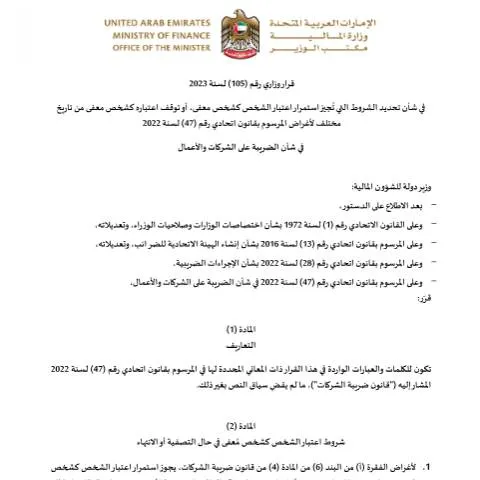
Understanding Ministerial Decision No. 105 of 2023 on Tax Exemption Status in the UAE
The United Arab Emirates has recently issued Ministerial Decision No. 105 of 2023, which clarifies the conditions under which an individual or entity continues to be recognized as exempt from certain tax obligations. This decision is a significant development in the UAE's ongoing efforts to streamline tax regulations and ensure compliance within the framework of Federal Law No. 47 of 2022 concerning corporate and business taxation.
Scope and Objectives of the Decision
The primary purpose of Ministerial Decision No. 105/2023 is to define the specific criteria that allow a person or a legal entity to maintain their status as a tax-exempt individual or organization. It also establishes the circumstances under which this exemption status may be revoked or suspended. These provisions aim to promote transparency, prevent misuse of tax exemptions, and ensure that the exemption status aligns with the evolving legal and economic landscape of the UAE.
Key Provisions and Conditions
Criteria for Continued Tax Exemption
The decision sets out detailed conditions that an individual or entity must meet to retain their tax exemption status. These include, but are not limited to:
- Compliance with all relevant legal and regulatory requirements as stipulated by the Federal Tax Authority (FTA).
- Adherence to specific operational or activity-based criteria that justify exemption status.
- Maintenance of accurate and up-to-date records demonstrating eligibility for exemption.
Conditions for Revocation or Suspension
The decision also specifies the grounds on which an exemption status may be revoked or suspended. These include:
- Failure to meet the criteria established for exemption over a specified period.
- Engagement in activities that contradict the original purpose of exemption or violate applicable laws.
- Provision of false or misleading information during the application or renewal process.
Implications for Taxpayers and Exempt Entities
Entities and individuals benefiting from tax exemptions should review their status regularly in light of this decision. Ensuring compliance with the outlined conditions is essential to avoid potential revocation, which could lead to additional tax liabilities and penalties.
Taxpayers are advised to maintain comprehensive documentation demonstrating their adherence to the exemption criteria. This includes financial records, activity reports, and correspondence with the Federal Tax Authority (FTA) or other relevant authorities.
Procedural Aspects and Compliance
The decision emphasizes the importance of proactive management of exemption status through digital channels. The UAE's robust digital infrastructure, including the FTA's online portal and other federal and emirate-level digital services, facilitates the submission of necessary documents, renewal applications, and status updates.
Individuals and entities should regularly consult the official portals of the Federal Tax Authority and relevant emirate authorities to stay informed about any updates or procedural requirements related to exemption status.
Conclusion
Ministerial Decision No. 105 of 2023 marks a significant step towards clarifying the regulatory framework governing tax exemptions in the UAE. By establishing clear criteria and procedures, it aims to foster a compliant and transparent tax environment. Stakeholders are encouraged to familiarize themselves with these provisions and leverage the digital platforms provided by authorities to ensure ongoing compliance and avoid disruptions to their exemption status.