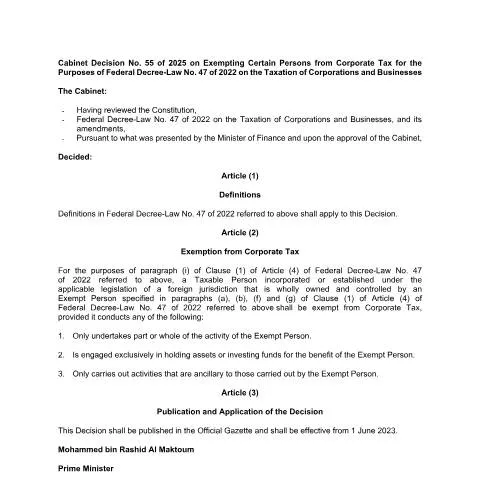
Overview of Cabinet Decision No. 55 of 2025 on Corporate Tax Exemptions in the UAE
The United Arab Emirates continues to refine its fiscal framework to promote economic growth and attract diverse business activities. A significant development in this area is the issuance of Cabinet Decision No. 55 of 2025, which addresses the exemption of specific entities and individuals from corporate tax obligations in accordance with the provisions of Federal Decree-Law No. 47 of 2022 on the taxation of corporations and businesses. This decision aims to clarify eligibility criteria and streamline the application of tax exemptions, fostering a more investor-friendly environment.
Scope and Purpose of the Decision
This cabinet decision provides detailed guidance on the scope of corporate tax exemptions granted to certain persons and entities operating within the UAE. It delineates the categories of eligible taxpayers and specifies the conditions under which exemptions apply. The primary objective is to support strategic sectors, small and medium-sized enterprises (SMEs), and specific categories of individuals who contribute to the UAE’s economic diversification and sustainable development goals.
By establishing clear criteria for exemption, the decision enhances compliance and simplifies administrative procedures. It also aligns with the UAE’s broader fiscal policy, which emphasizes transparency, digital efficiency, and ease of doing business.
Who Is Eligible for the Exemptions?
The decision identifies several categories of persons and entities that may benefit from corporate tax exemptions, including but not limited to:
- Entities operating within designated free zones, provided they meet specific criteria outlined by the relevant authorities.
- Small and medium-sized enterprises (SMEs) contributing to key economic sectors.
- Certain international companies engaged in activities aligned with national development objectives.
- Individuals involved in qualifying business activities, especially those in innovative or strategic sectors.
Eligibility is subject to compliance with registration and reporting requirements set forth by the Federal Tax Authority (FTA) and relevant emirate-level authorities. Applicants must ensure that their activities fall within the scope of the exemption categories and adhere to applicable legal and regulatory frameworks.
Key Provisions and Conditions
The decision elaborates on several important provisions, including:
- Application Procedures: Eligible persons and entities should submit their exemption requests via the official channels provided by the Federal Tax Authority or respective emirate authorities. Digital platforms are emphasized to facilitate efficient processing.
- Documentation Requirements: Applicants must provide supporting documents demonstrating eligibility, such as business registration certificates, proof of activity, and compliance with relevant regulations.
- Duration and Renewal: The exemption period and renewal conditions are specified, encouraging ongoing compliance and reporting.
- Limitations and Exceptions: The decision clarifies circumstances where exemptions may be revoked or not granted, ensuring transparency and legal clarity.
Implications for Taxpayers and Business Community
The issuance of Cabinet Decision No. 55 of 2025 is a strategic move to promote investment and economic diversification in the UAE. Entities benefiting from these exemptions can enjoy reduced tax burdens, thereby enhancing their competitiveness and operational capacity.
Furthermore, the decision underscores the UAE’s commitment to a transparent and digitally integrated tax environment. It encourages taxpayers to leverage the digital portals provided by the Federal Tax Authority and other relevant bodies for application, compliance, and reporting purposes.
References and Authority
This decision is issued by the Cabinet of the United Arab Emirates and is aligned with the provisions of Federal Decree-Law No. 47 of 2022 concerning corporate taxation. It is implemented and overseen by the Federal Tax Authority (FTA), which is responsible for ensuring compliance and facilitating the application of exemptions.
For detailed guidance and official updates, taxpayers are advised to consult the relevant official portals of the Federal Tax Authority and the UAE government’s digital services platform.