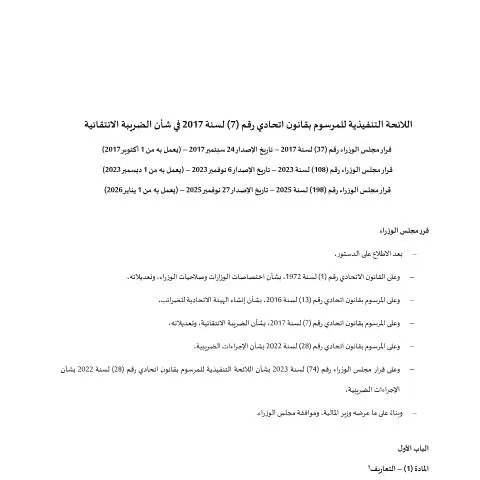
Understanding the Executive Regulation of Federal Decree-Law No. 7 of 2017 on Excise Tax in the UAE
The Cabinet Decision No. 37 of 2017, issued by the United Arab Emirates (UAE) Council of Ministers, establishes the executive regulation governing Federal Decree-Law No. 7 of 2017 concerning excise tax. This regulation provides a detailed framework for the implementation, administration, and compliance procedures related to excise tax within the UAE, ensuring alignment with national fiscal policies and international standards.
Scope and Objectives of the Regulation
This executive regulation aims to clarify the operational aspects of the excise tax law, which was introduced to regulate the production, importation, and consumption of specific goods deemed harmful to health or the environment. Its scope encompasses all entities involved in the supply chain of excise goods, including manufacturers, importers, and consumers, across the seven emirates.
The primary objectives are to:
- Define the procedures for registration and licensing of excise tax registrants.
- Establish the mechanisms for tax calculation, collection, and reporting.
- Set out the obligations for record-keeping, compliance, and audits.
- Provide guidance on penalties and enforcement measures for non-compliance.
Main Provisions and Administrative Procedures
Registration and Licensing
Entities involved in the manufacturing or importation of excise goods are required to register with the Federal Tax Authority (FTA). The regulation details the registration process, documentation requirements, and licensing procedures, emphasizing the importance of digital submission through the FTA’s online platform.
Tax Calculation and Payment
The regulation specifies how excise tax should be calculated based on the type and quantity of goods. It mandates timely payment of taxes through the FTA’s electronic systems, ensuring efficient and transparent collection processes. Taxpayers must also maintain accurate records of their transactions for audit purposes.
Record-Keeping and Compliance
All registrants are obligated to keep detailed records of their operations, including production, importation, and distribution activities. These records must be preserved for a specified period and made available for review during audits conducted by the FTA. The regulation encourages the use of digital record-keeping to streamline compliance and reporting.
Enforcement and Penalties
The regulation outlines various penalties for violations, including failure to register, underreporting, or non-payment of excise tax. Enforcement measures are designed to uphold compliance and are enforced by the relevant authorities, with penalties aligned with the UAE’s broader legal framework on tax violations.
Implications for Businesses and Consumers
For businesses involved in the production or importation of excise goods, this regulation underscores the importance of adhering to registration, reporting, and payment obligations. It also emphasizes the need for robust record-keeping and compliance systems, preferably integrated with the digital platforms provided by the FTA.
Consumers are indirectly affected through the increased prices of excise goods, which are part of the government’s strategy to reduce consumption of harmful products. The regulation ensures that the excise tax is applied fairly and collected efficiently, supporting the UAE’s broader health and environmental policies.
Digitalization and Future Developments
The UAE’s commitment to digital government services is reflected in this regulation’s emphasis on electronic registration, reporting, and record-keeping. The FTA’s online portal serves as the central platform for all excise tax-related activities, facilitating ease of compliance and real-time monitoring.
As the regulatory environment evolves, businesses and stakeholders should stay informed about updates to the executive regulation and related procedures. The UAE’s proactive approach aims to enhance transparency, efficiency, and compliance in tax administration, aligning with its vision for a sustainable and digitally advanced economy.
Conclusion
The Cabinet Decision No. 37 of 2017 on the executive regulation of the excise tax law provides a comprehensive legal framework to support the effective implementation of excise taxes in the UAE. It emphasizes digital integration, transparency, and compliance, ensuring that all stakeholders understand their responsibilities and the operational procedures involved. For further information and detailed guidance, entities are advised to consult the official resources provided by the Federal Tax Authority and relevant government portals.